

Phone, travel and housing support is not automatically included in the social insurance salary merely because it is paid at a fixed monthly amount. According to Official Letter 6101/BHXH-QLT dated 31/7/2026 from Ho Chi Minh City Social Insurance, the key factors are the substance of the agreement and how the company records the payment in labor documents. Therefore, your company should separate salary from support payments from the employment contract stage instead of merely renaming items on the payroll.
The decisive issue is not whether a payment is labeled “support” or “welfare,” but whether the employment contract, internal rules, payroll and payment documents are consistent. If the records show that a payment is substantively salary, a different label is not enough to exclude it from the social insurance contribution base. A safer approach is to identify the true nature, record the payment separately and retain sufficient documentation for explanations during inspections.
📌 Key points to remember
- Phone, travel and housing support is not automatically included in the social insurance salary, even when paid at a fixed monthly amount.
- The decisive factors are the nature of the payment and the consistency of the records, not the label “support” or “welfare.”
- The employment contract is the primary basis; each support payment should be recorded as a separate item with the correct purpose, recipients and payment method.
- The company self-declares, bears responsibility and must retain sufficient records to explain when the social insurance authority inspects and reconciles.
- Official Letter 6101/BHXH-QLT answers only a specific case — a separate review is needed before changing the salary structure.
Support payments are not automatically subject to social insurance contributions
Official Letter 6101/BHXH-QLT states that phone, travel and housing support that is not salary does not form part of the social insurance contribution base. This remains the case even when the support amount is fixed and paid regularly each month. However, your company must be able to demonstrate that the payment is genuinely support and not a portion of salary renamed to reduce contributions.
The social insurance salary is determined based on the agreements stated in the employment contract and related records. Therefore, each support payment should be shown as a separate item with its purpose, eligible recipients and payment method correctly reflected. Recording only one total income figure and then internally splitting it into salary and support can create risks when records are cross-checked.
Distinguishing support payments from payments that are substantively salary
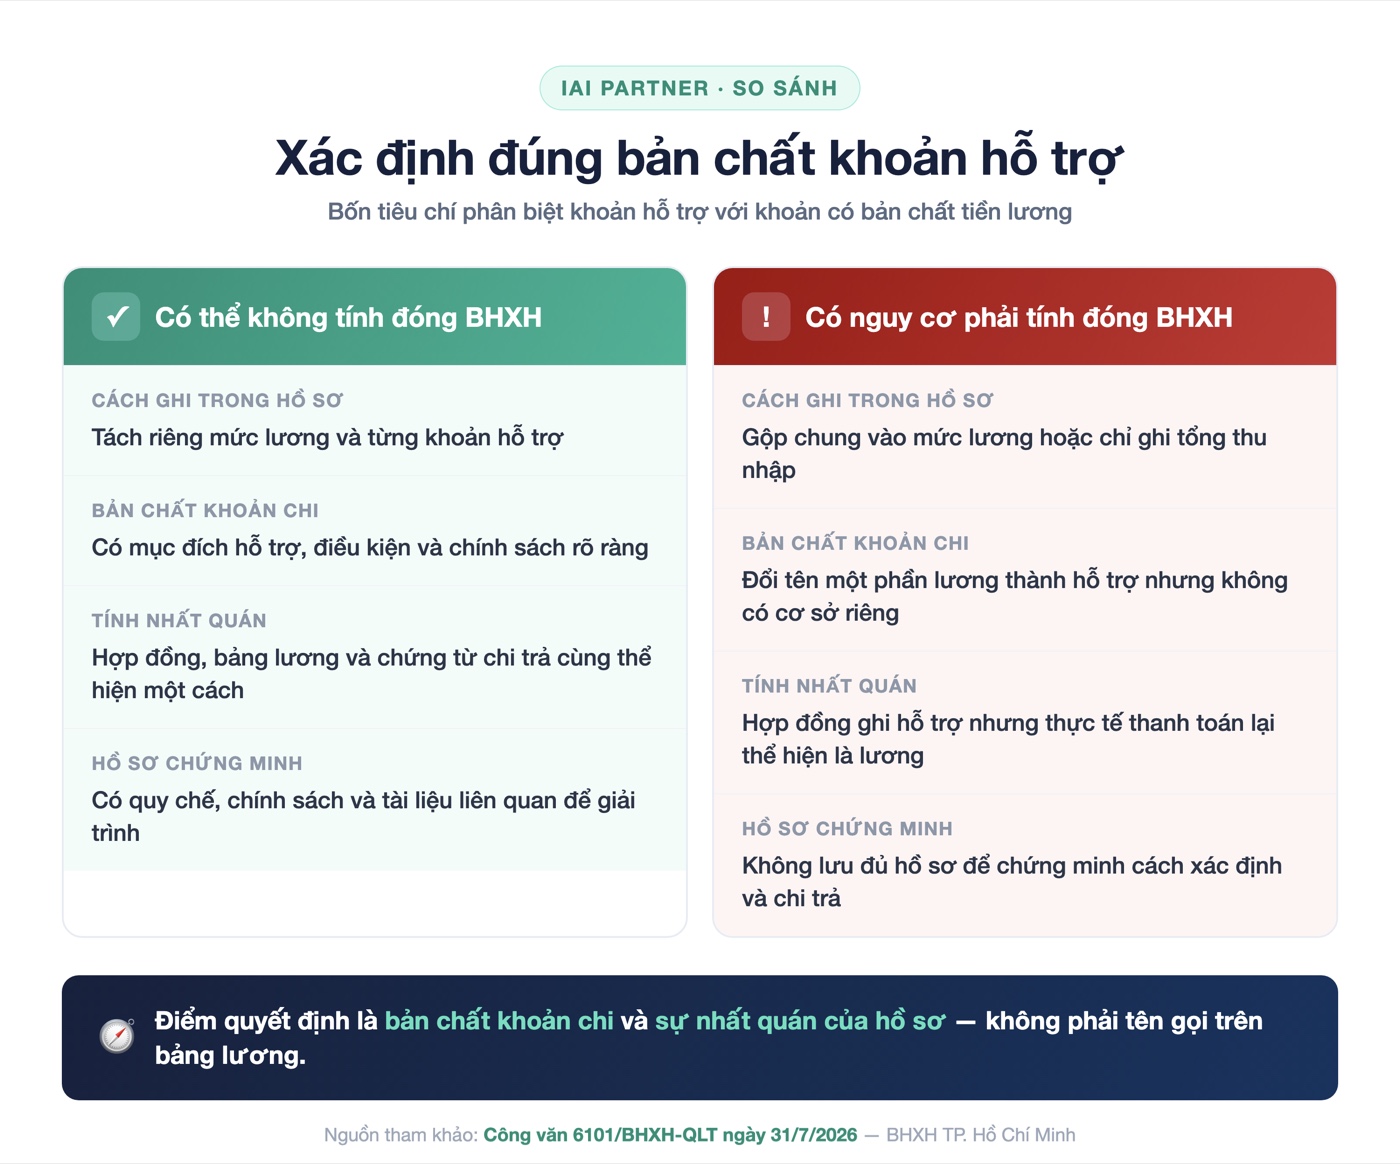
A support payment may be considered for exclusion from the social insurance contribution base when it is separately stated in the contract or appendix, supported by internal rules and paid for its stated purpose. Payroll records, payment documents and accounting treatment should reflect the same nature. Conversely, a payment may be treated as salary if it guarantees a fixed income level, compensates for salary otherwise payable, or is directly tied to job title and work performance.
| Criteria | May be excluded from social insurance contributions | Risk of being included in social insurance contributions |
|---|---|---|
| How it is recorded | Salary and each support payment are stated separately | Combined with salary or shown only as total income |
| Nature of the payment | Clear support purpose, conditions and policy | Part of salary is renamed as support without a separate basis |
| Consistency | Contract, payroll and payment documents reflect the same treatment | The contract states support, but actual payment is shown as salary |
| Supporting documentation | Internal rules, policies and related documents are retained for explanation | Insufficient records to prove how the payment was determined and paid |
The employment contract is the starting point for determining the contribution base
According to the source material, the employment contract is the primary basis for determining the social insurance salary. your company should state the salary, allowances and each support payment as separate items to avoid presenting all income as one salary component. When the income structure changes, the contract appendix and related operational documents should also be updated accordingly.
A label cannot replace the true nature of a labor payment
Calling a payment “phone support” or “housing support” is not enough to conclude that it is excluded from social insurance contributions. If the payment actually guarantees an agreed salary level or replaces part of salary, the risk of reassessment remains. The company should design the policy around the genuine support purpose rather than merely changing the label on documents.
The documentation chain must be consistent from agreement to payment
A support payment is safer from a documentation perspective only when all records reflect the same nature. The employment contract should separately state the support item, while internal rules should define eligible recipients, amounts, conditions and payment methods. Payroll should present the item separately, and payment documents should match the payroll and the issued internal rules.
- The employment contract separately states salary and each support payment.
- A contract appendix is prepared when the company changes the salary, allowance or support structure.
- Salary rules and welfare policies define the purpose, eligible recipients, conditions and benefit levels.
- Payroll, attendance records and payment documents are retained to reconcile calculations with actual payments.
- Related internal records are retained by employee and payroll period to facilitate explanations.
The company self-declares and must be ready to explain
According to Official Letter 6101/BHXH-QLT, when registering an increase or adjusting the contribution level, the social insurance authority does not require the company to immediately submit invoices proving support payments. This does not mean supporting documentation is unnecessary. The company still self-declares, bears responsibility for the declaration and must retain documents for inspection and reconciliation when requested.
An important inspection principle is that the records must not conflict among the agreement, accounting treatment and actual payment.
Four common risks when separating support payments from salary
Risks often arise when a company focuses on the form of documents without controlling the actual substance. The social insurance authority may review contracts, appendices, payroll, attendance records, internal rules and payment documents to assess consistency. Therefore, reducing the social insurance salary without simultaneously updating the documentation and operating process may trigger requests for explanation.
- Different name, same substance: the support payment is still used to guarantee a fixed salary level or compensate for salary otherwise payable.
- Inconsistent records: the contract states support, but payroll, accounting entries or transfer descriptions show salary.
- No internal rules: the company cannot establish the purpose, eligible recipients, benefit conditions or basis for setting the support amount.
- Insufficient documentation for structural changes: the social insurance salary is reduced without preparing an appendix or fully updating payroll and related records.
Review process before changing the income structure
Before changing the salary and welfare structure, your company should review the entire current documentation rather than adjusting only the payroll. Classifying each income component helps identify salary, salary allowances, additional payments and other welfare benefits. The employment contract, appendices, internal rules, payroll, accounting treatment and payment descriptions should then be updated consistently.
- Review the current situation using employment contracts, appendices, payroll, internal rules and payment documents.
- Classify each income component by substance rather than relying only on its label.
- Standardize contracts, appendices and internal rules so they accurately reflect the policy being implemented.
- Update payroll, accounting treatment and payment descriptions using the same presentation.
- Conduct periodic checks and retain evidence for reconciliation and explanation when needed.
For fast and consistent implementation, your company may refer to IAI Partner’s payroll service.
How to standardize records and figures is described in the proactive accounting process.
Official Letter 6101/BHXH-QLT must be used within the proper scope
The source material notes that Official Letter 6101/BHXH-QLT is a response to a specific case and is not a generally applicable normative legal document. Therefore, your company should not rely on this letter alone as the sole basis for redesigning the entire salary structure. Before adjusting contribution levels, labor law, social insurance law and the actual records of each employee group should be reviewed together.
For complex income structures, each payment should be assessed separately based on the agreement and actual implementation. A fixed monthly support payment does not automatically become salary, but it is also not automatically excluded from the social insurance salary. The decisive factors remain the substance of the payment and the ability to prove it through a consistent documentation system.
Frequently asked questions
Are fixed monthly phone, travel and housing support payments subject to social insurance contributions?
According to Official Letter 6101/BHXH-QLT, these payments may be excluded from the social insurance contribution base if they are genuinely support and are separately recorded. your company should still ensure that the employment contract, internal rules, payroll and payment documents consistently reflect the same nature.
Is renaming part of salary as support enough to reduce the social insurance contribution level?
No. The label “support” is not sufficient if the payment is substantively salary or is used to compensate for salary otherwise payable. The labor records and actual payment method must demonstrate an independent support purpose.
When adjusting the social insurance contribution level, must the company immediately submit invoices proving support payments?
According to Official Letter 6101/BHXH-QLT, the social insurance authority does not require immediate invoice submission when registering an increase or adjusting the contribution level. The company must still self-declare, retain related records and be ready to explain when the competent authority conducts an inspection.
Recommendations from IAI Partner
Dear Valued Enterprise,
Optimizing the income structure should not begin by renaming salary as support. your company should first determine the nature of each payment, then standardize the employment contract, internal rules, payroll and payment documents so they present it consistently.
For phone, travel, housing or similar welfare payments, the records should clearly show the support purpose, eligible recipients and basis for determining the amount. Consistency between the agreement and actual payment is important when the company must provide an explanation.
Official Letter 6101/BHXH-QLT is reference material for a specific case, so each company should conduct its own review before adjusting the social insurance contribution level.
Need support? IAI Partner can review the income structure, labor records and payroll process so your company can identify inconsistencies before making adjustments.
Sincerely,
iai Partner®
Source: IAI-Partner.com
Related content
- Professional payroll service
- Proactive accounting process
- Social insurance service
- HR and payroll management
- Decree 291/2026/NĐ-CP: controlling requests for tax information
- Corporate accounting & finance knowledge
Need help? Contact IAI Partner
📞 Hotline: 033 944 7112
📧 Email: hi@iai-partner.com
🌐 Website: iai-partner.com