

📌 Key points to remember
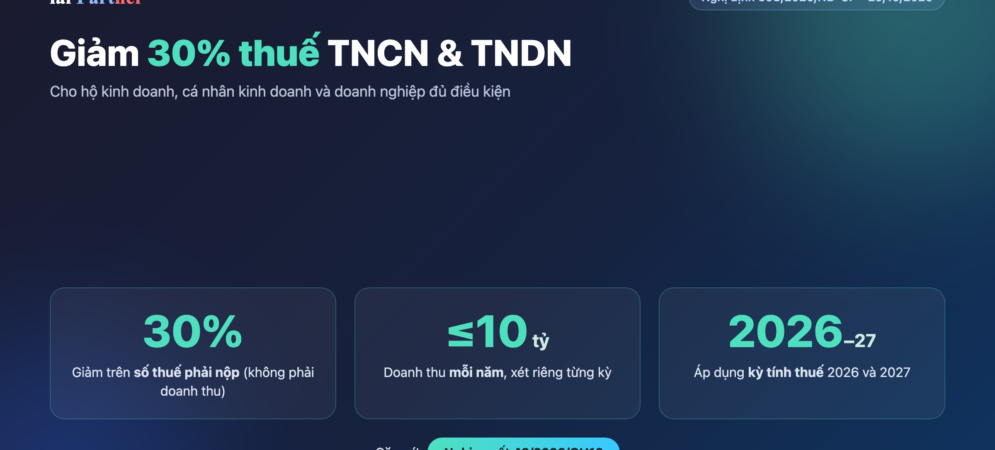
- 30% reduction: Eligible taxpayers receive a 30% of tax payable for tax years 2026 and 2027.
- VND 10 billion threshold: The revenue condition is annual revenue not exceeding VND 10 billion for each tax year.
- Business PIT: The PIT reduction applies only to production and business income, không áp dụng tiền lương, tiền công.
- After incentives: Enterprises with CIT incentives calculate the reduction on tax remaining payable after incentives.
- Track actual revenue: If actual revenue exceeds VND 10 billion, the reduced tax amount must be reviewed, adjusted and additionally paid under the regulations.
Ngày 29 October 2026, Chính phủ ban hành Decree 398/2026/NĐ-CP Resolution 43/2026/QH1629 October 2026 and applies to tax years 2026 and 2027.
The key point is that the policy reduces 30% of tax payable, not a 30% reduction of revenue or profit. The revenue threshold for eligibility isannual revenue not exceeding VND 10 billion, and must be assessed separately for each tax period, 2026 and 2027.
Who is eligible for the 30% PIT reduction?
Under Article 2, the policy applies to resident individuals engaged in production or business activities, including household business registrants or persons authorized to represent a household business. Revenue eligibility is assessed separately for 2026 and 2027, with annual revenue not exceedingVND 10 billion.
30%
PIT reduction on business income
Calculated on PIT payable arising from all production and business income.
⚠️ Not applicable to salary income
The PIT reduction under Decree 398/2026/NĐ-CP applies to business income. People who only earn salary or wages are not covered by this 30% reduction.
Who is eligible for the 30% CIT reduction?
Article 3 applies to enterprises and organizations established under Vietnamese law, including companies, cooperatives, cooperative unions, public service units and other income-generating organizations. The main condition is annual revenue in 2026 or 2027 not exceeding VND 10 billion.
If an enterprise already enjoys tax incentives under the Corporate Income Tax Law or other laws or National Assembly resolutions, the 30% reduction is calculated on tax payable after incentives have been deducted. This distinction avoids incorrectly applying 30% to tax before incentives.
Comparison of PIT and CIT reductions
| Criteria | TNCN | TNDN |
|---|---|---|
| Eligible taxpayer | Resident individual carrying on business | Enterprise or organization established under Vietnamese law |
| Revenue threshold | Not more than VND 10 billion/year | Not more than VND 10 billion/year |
| Reduction | 30% of tax payable | 30% of tax payable |
How is the VND 10 billion revenue threshold determined for enterprises?
Annual revenue used to determine CIT eligibility is not limited to sales. Under the Decree, it includes sales, service revenue, financial revenue and other income. Revenue of dependent units or business locations shown in annual consolidated financial statements is also included.
⚠️ Do not look only at sales revenue
If an enterprise compares only invoice sales revenue with the VND 10 billion, the conclusion may be wrong. Fully review service revenue, financial revenue, other income and the revenue of dependent units per the financial statements.
Cases of enterprise division or separation after 24 August 2026
Resolution 43/2026/QH1624 August 2026. The CIT reduction does not apply to enterprises formed through division or separation after that date if the total annual revenue of all resulting enterprises exceeds VND 10 billion. The review must consider combined revenue, not each entity separately.
Filing and adjustment when actual revenue exceeds the threshold
For individual businesses
An individual business expecting revenue not exceeding VND 10 billion claims the reduction using Form 01. Those withholding, filing or paying on behalf use Form 02. If cumulative actual revenue exceeds VND 10 billion, the individual must adjust using Form 03 and pay back the reduction.
For enterprises
An enterprise expecting revenue not exceeding VND 10 billion may determine the CIT reduction itself when making quarterly provisional payments. If actual year-end revenue exceeds the threshold, it must recalculate and pay the shortfall. Tracking cumulative revenue during the year is therefore essential.
| Case | Handling |
|---|---|
| Eligible individual based on forecast | File Form 01 |
| Withholding or filing/paying on behalf | File Form 02 |
| Individual exceeds actual threshold | Adjust using Form 03 and pay additional tax |
| Enterprise exceeds actual threshold | Recalculate and pay the tax shortfall |
What if tax was filed without claiming the reduction?
For individual businesses that filed PIT without the reduction, the Decree allows adjustment or supplementary filing, or determination of the reduction at annual finalization. Overpaid tax may be offset or refunded under tax administration rules.
✅ Previously filed returns can still be adjusted
Do not give up the benefit merely because a return was already filed. Recheck eligibility for 2026 and 2027, the tax already declared and amounts that can be adjusted or handled as overpaid tax.
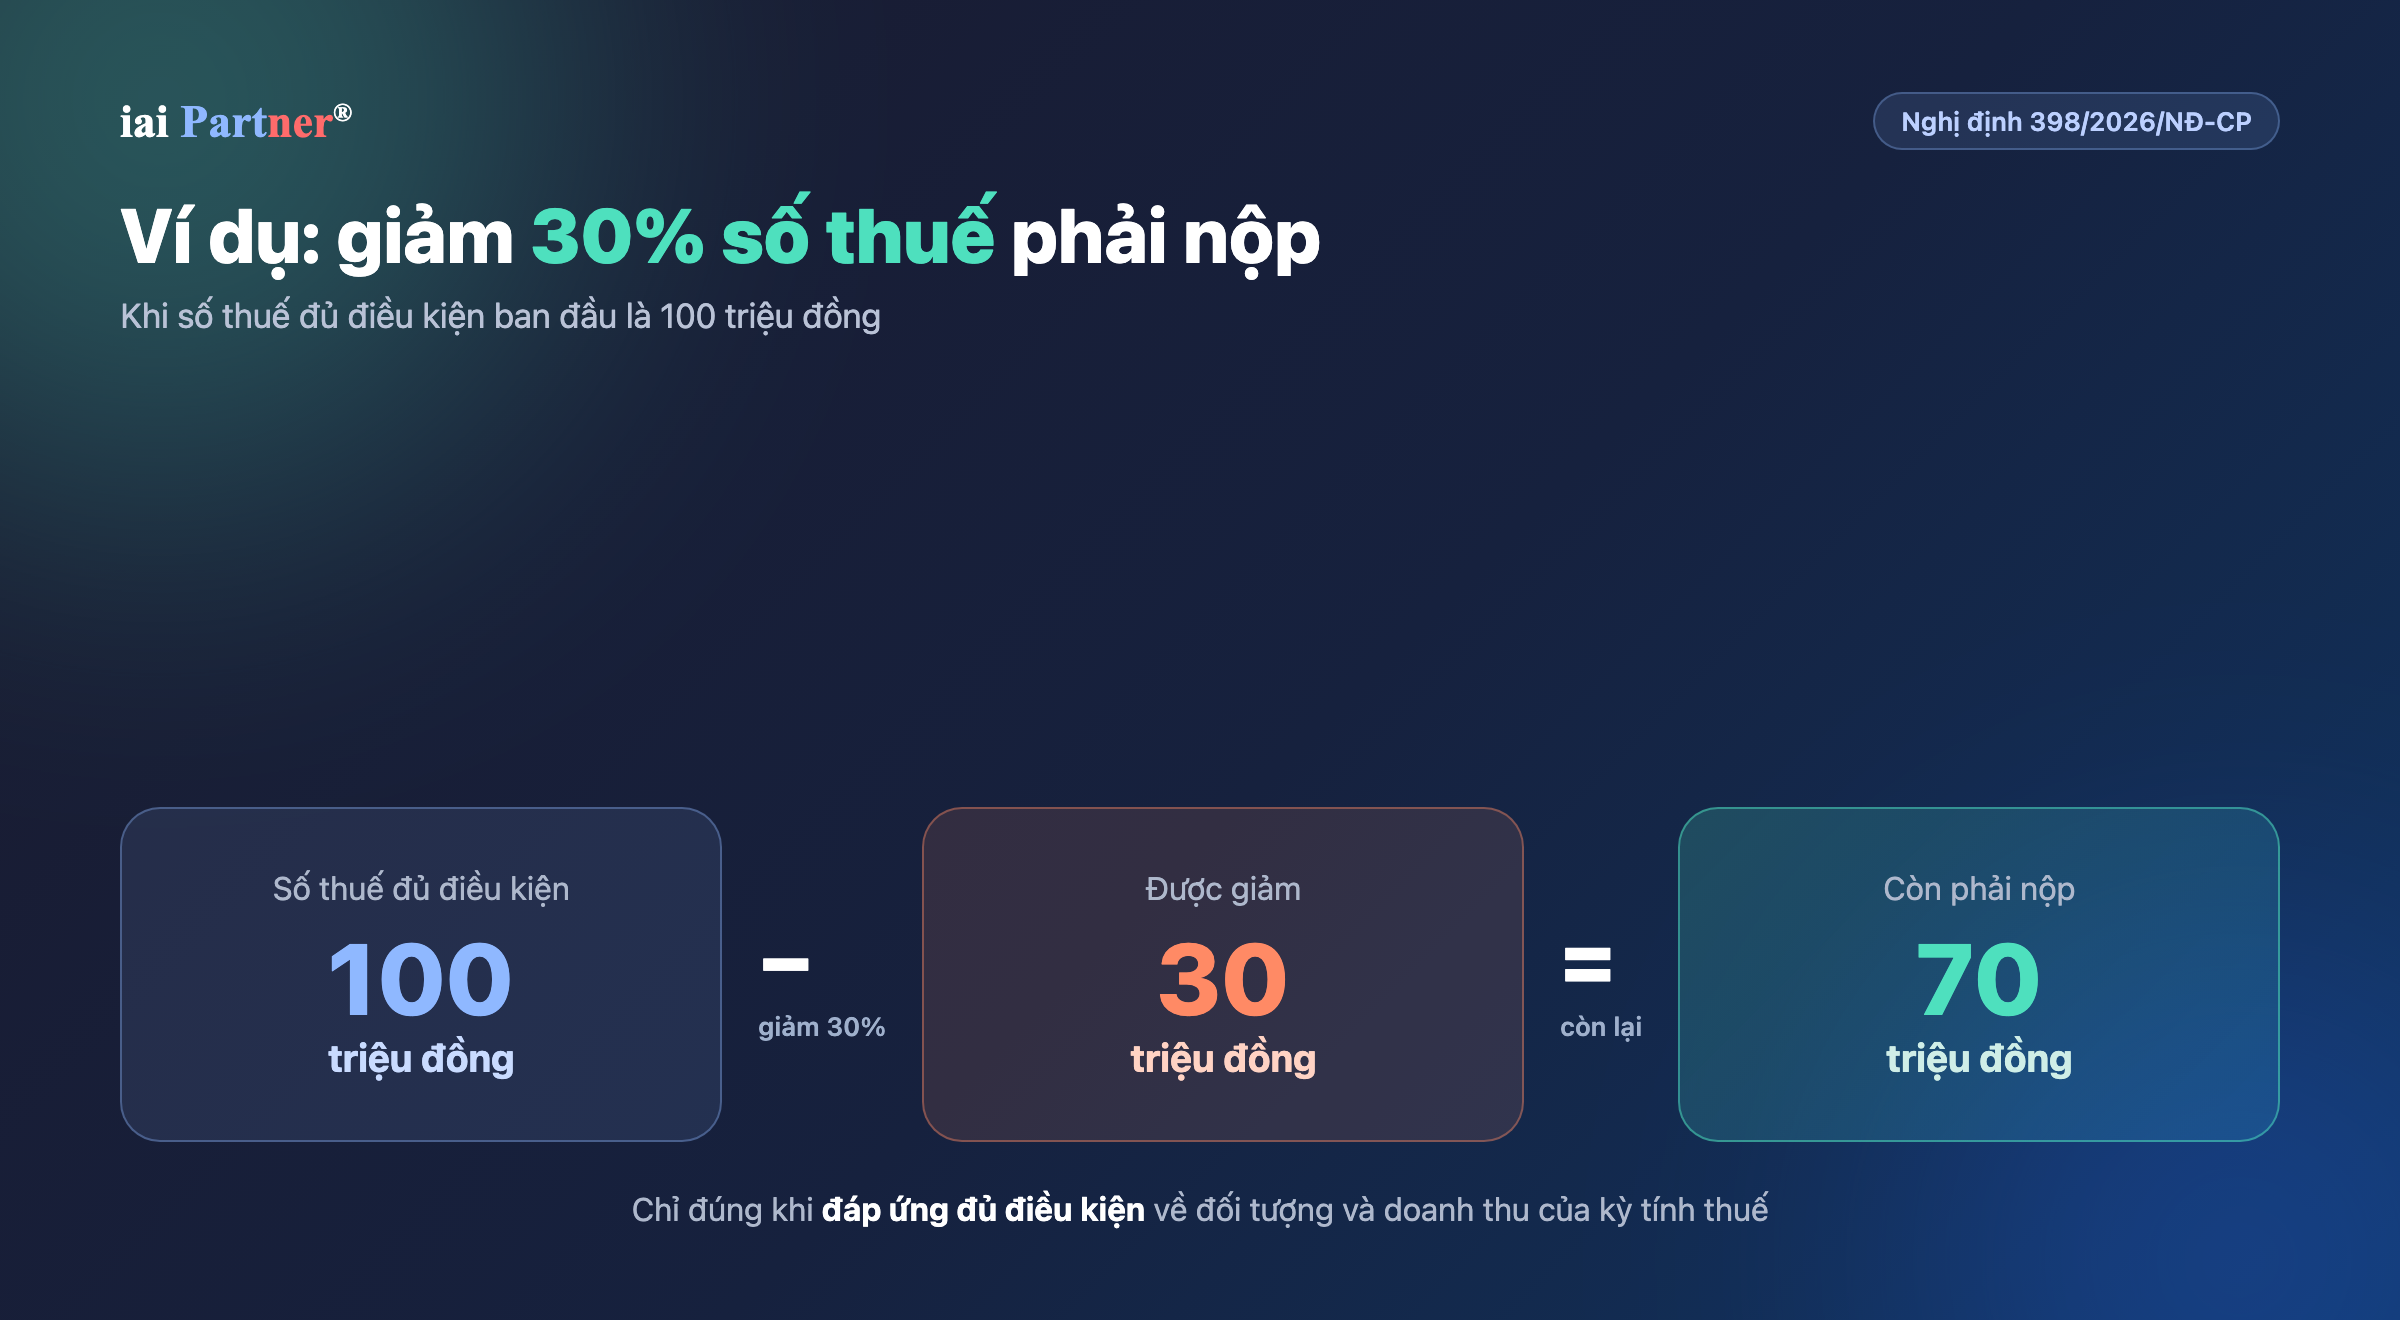
Example: How much remains from VND 100 million tax after the reduction?
VND 70 million
Tax remaining payable
If eligible tax is VND 100 million, the 30% reduction equalsVND 30 million.
Calculation: VND 100 million × 30% = VND 30 million reduction, leaving VND 70 million payable. This applies only if the taxpayer fully satisfies the eligibility and revenue conditions for the relevant tax year.
What should businesses and household businesses do now?
- Review actual and projected revenue separately for2026 and 2027.
- For enterprises, include sales, services, financial revenue, other income and revenue of dependent units.
- Check whether the enterprise receives CIT incentives to determine the correct tax base for the 30% reduction.
- Individual businesses should use the correct Form 01, 02 or 03 for the actual filing situation.
- If tax was filed without the reduction, check supplementary filing, finalization adjustment or overpayment treatment.
💡 Track cumulative revenue; do not wait until year-end
The VND 10 billion threshold determines eligibility. Businesses and individual businesses should track cumulative revenue regularly to identify the risk of exceeding the threshold early.
Related services at IAI Partner
Frequently asked questions
Is revenue of exactly VND 10 billion eligible for the reduction?
Yes, if all other conditions are met. The rule uses not exceeding VND 10 billion, so revenue of exactly VND 10 billion is still within the limit.
Do salaried employees receive the 30% PIT reduction?
Not under this policy. The 30% PIT reduction in Decree 398/2026/NĐ-CP applies to income from production and business activities of eligible resident individuals.
Can an enterprise already receiving CIT incentives also get the 30% reduction?
Yes, if eligible. The 30% reduction is calculated on CIT payable after tax incentives have been deducted.
Recommendations from IAI Partner
Dear Valued Enterprise,
This tax reduction directly benefits enterprises and individual businesses with revenue not exceeding VND 10 billion. The benefit is secure only when revenue is correctly determined and tracked separately for tax years 2026 and 2027.
Enterprises should pay particular attention to financial revenue, other income and dependent-unit revenue; individual businesses should use Form 01, 02 or 03 as appropriate. A tax reduction should not turn into an additional tax bill merely because excess revenue is discovered only at year-end.
IAI Partner recommends maintaining a quarterly schedule of cumulative revenue and expected tax reduction. When accounting data, revenue and provisional tax payments are reconciled together, applying Decree 398/2026/NĐ-CP becomes clearer and less risky.
Sincerely,
iai Partner®
References
- Decree 398/2026/NĐ-CP ngày 29 October 2026 — A document guiding Resolution 43/2026/QH16 on PIT and CIT reductions; source: the Government Electronic Portal.
- Resolution 43/2026/QH16 — The legal basis for the 30% PIT and CIT reduction policy for tax years 2026 and 2027.
- Ministry of Finance – Detailed regulations on income tax reductions for individuals and businesses — A cross-reference source on eligible subjects, revenue, CIT incentives, declaration and handling of overpaid tax.
Source: IAI-Partner.com
Need help? Contact IAI Partner
📞 Hotline: 033 944 7112
📧 Email: hi@iai-partner.com
🌐 Website: iai-partner.com