

📌 Key points to remember
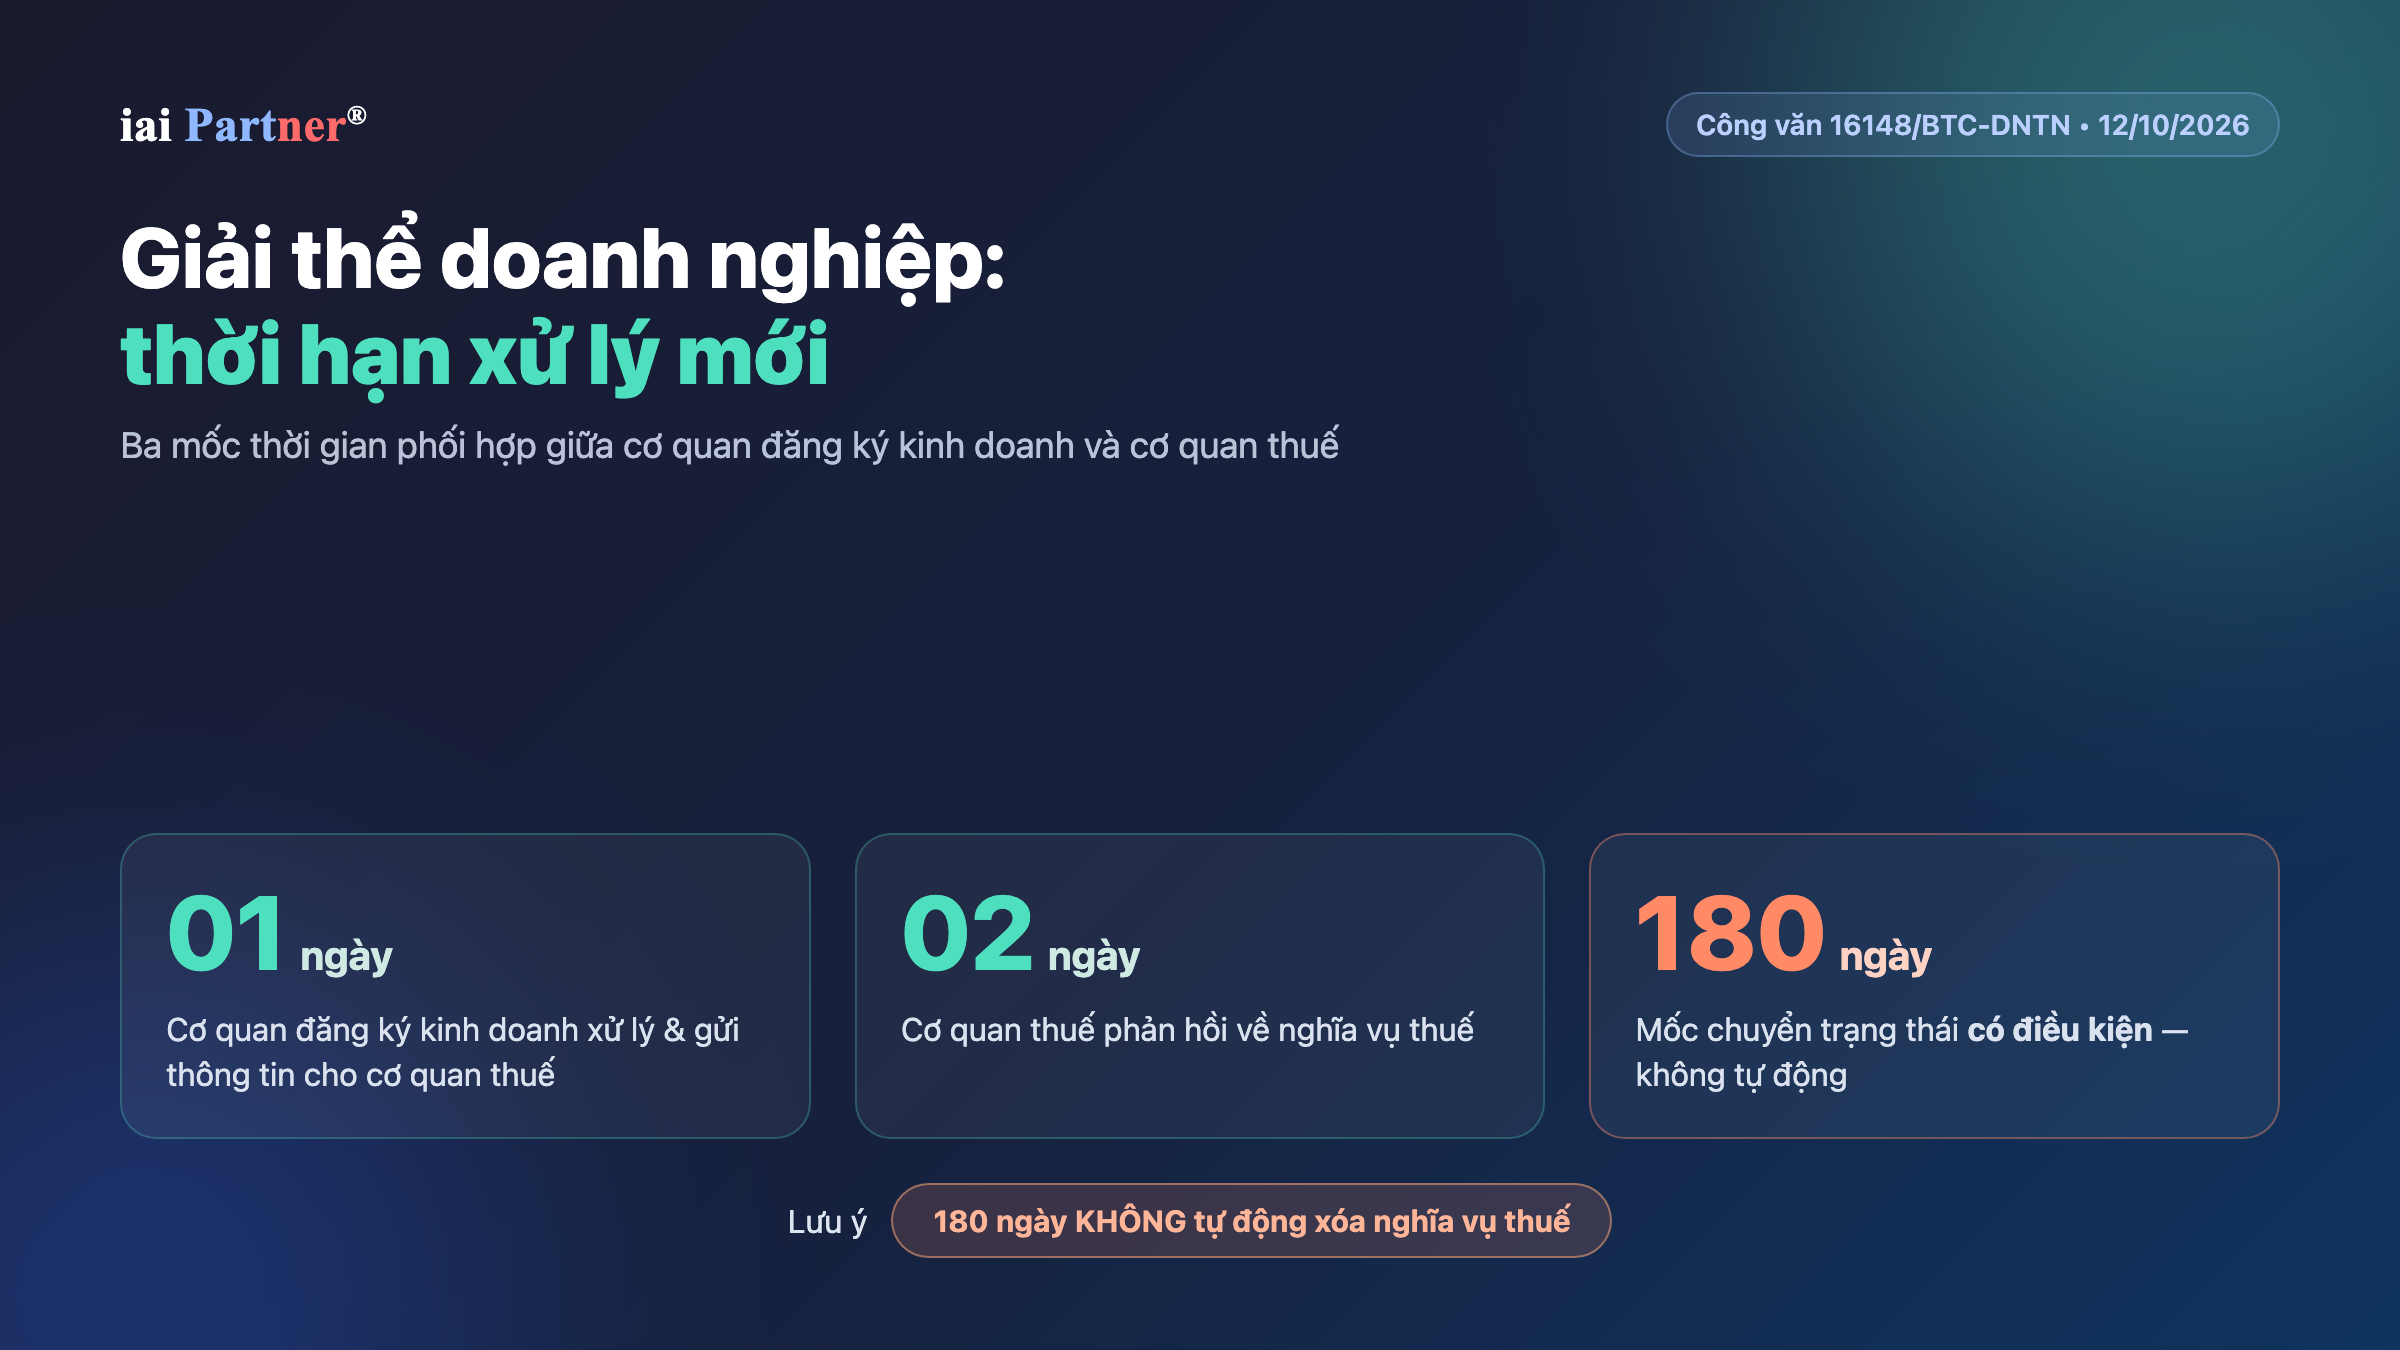
- 1 day: The business registration authority processes and sends information to the tax authority within 1 working day from receipt of the file.
- 2 days: The tax authority responds on tax obligations within 2 working days of receiving dissolution-registration information.
- 180-day: Mốc 180-day milestone leads to a status change only when the accompanying conditions are satisfied at the same time.
- 2 conditions: The business must settle all debts and property obligations and must not be in an ongoing dispute before a Court or Arbitration.
- No tax write-off: Processing deadlines do not automatically erase tax obligations; the business must still monitor and complete any outstanding obligations.
Ngày 12 October 2026, Bộ Tài chính ban hành Official Letter 16148/BTC-DNTN on accelerating business dissolution procedures. A key point is that the business registration authority and tax authority are required to coordinate under clearer processing milestones, making file progress easier for businesses to track.
However, shorter processing times do not mean a business may skip dissolution conditions or tax obligations. In particular, the 180-day milestone is a conditional status-change mechanism, not a rule that automatically terminates the tax code or erases tax obligations simply because the period has passed.
Conditions for a business to be dissolved
According to the source, dissolution rests on two basic conditions. First, the business must settle all debts and other property obligations. Second, it must not be in an ongoing dispute before a Court or Arbitration. These conditions should be checked before focusing only on procedural timelines.
⚠️ Faster timelines do not replace dissolution conditions
The official letter focuses on coordination speed between the business registration authority and the tax authority. The business must still ensure financial obligations are completed and no dispute is being resolved under the legal basis cited in the material.
The 1-day and 2-day milestones in the processing flow
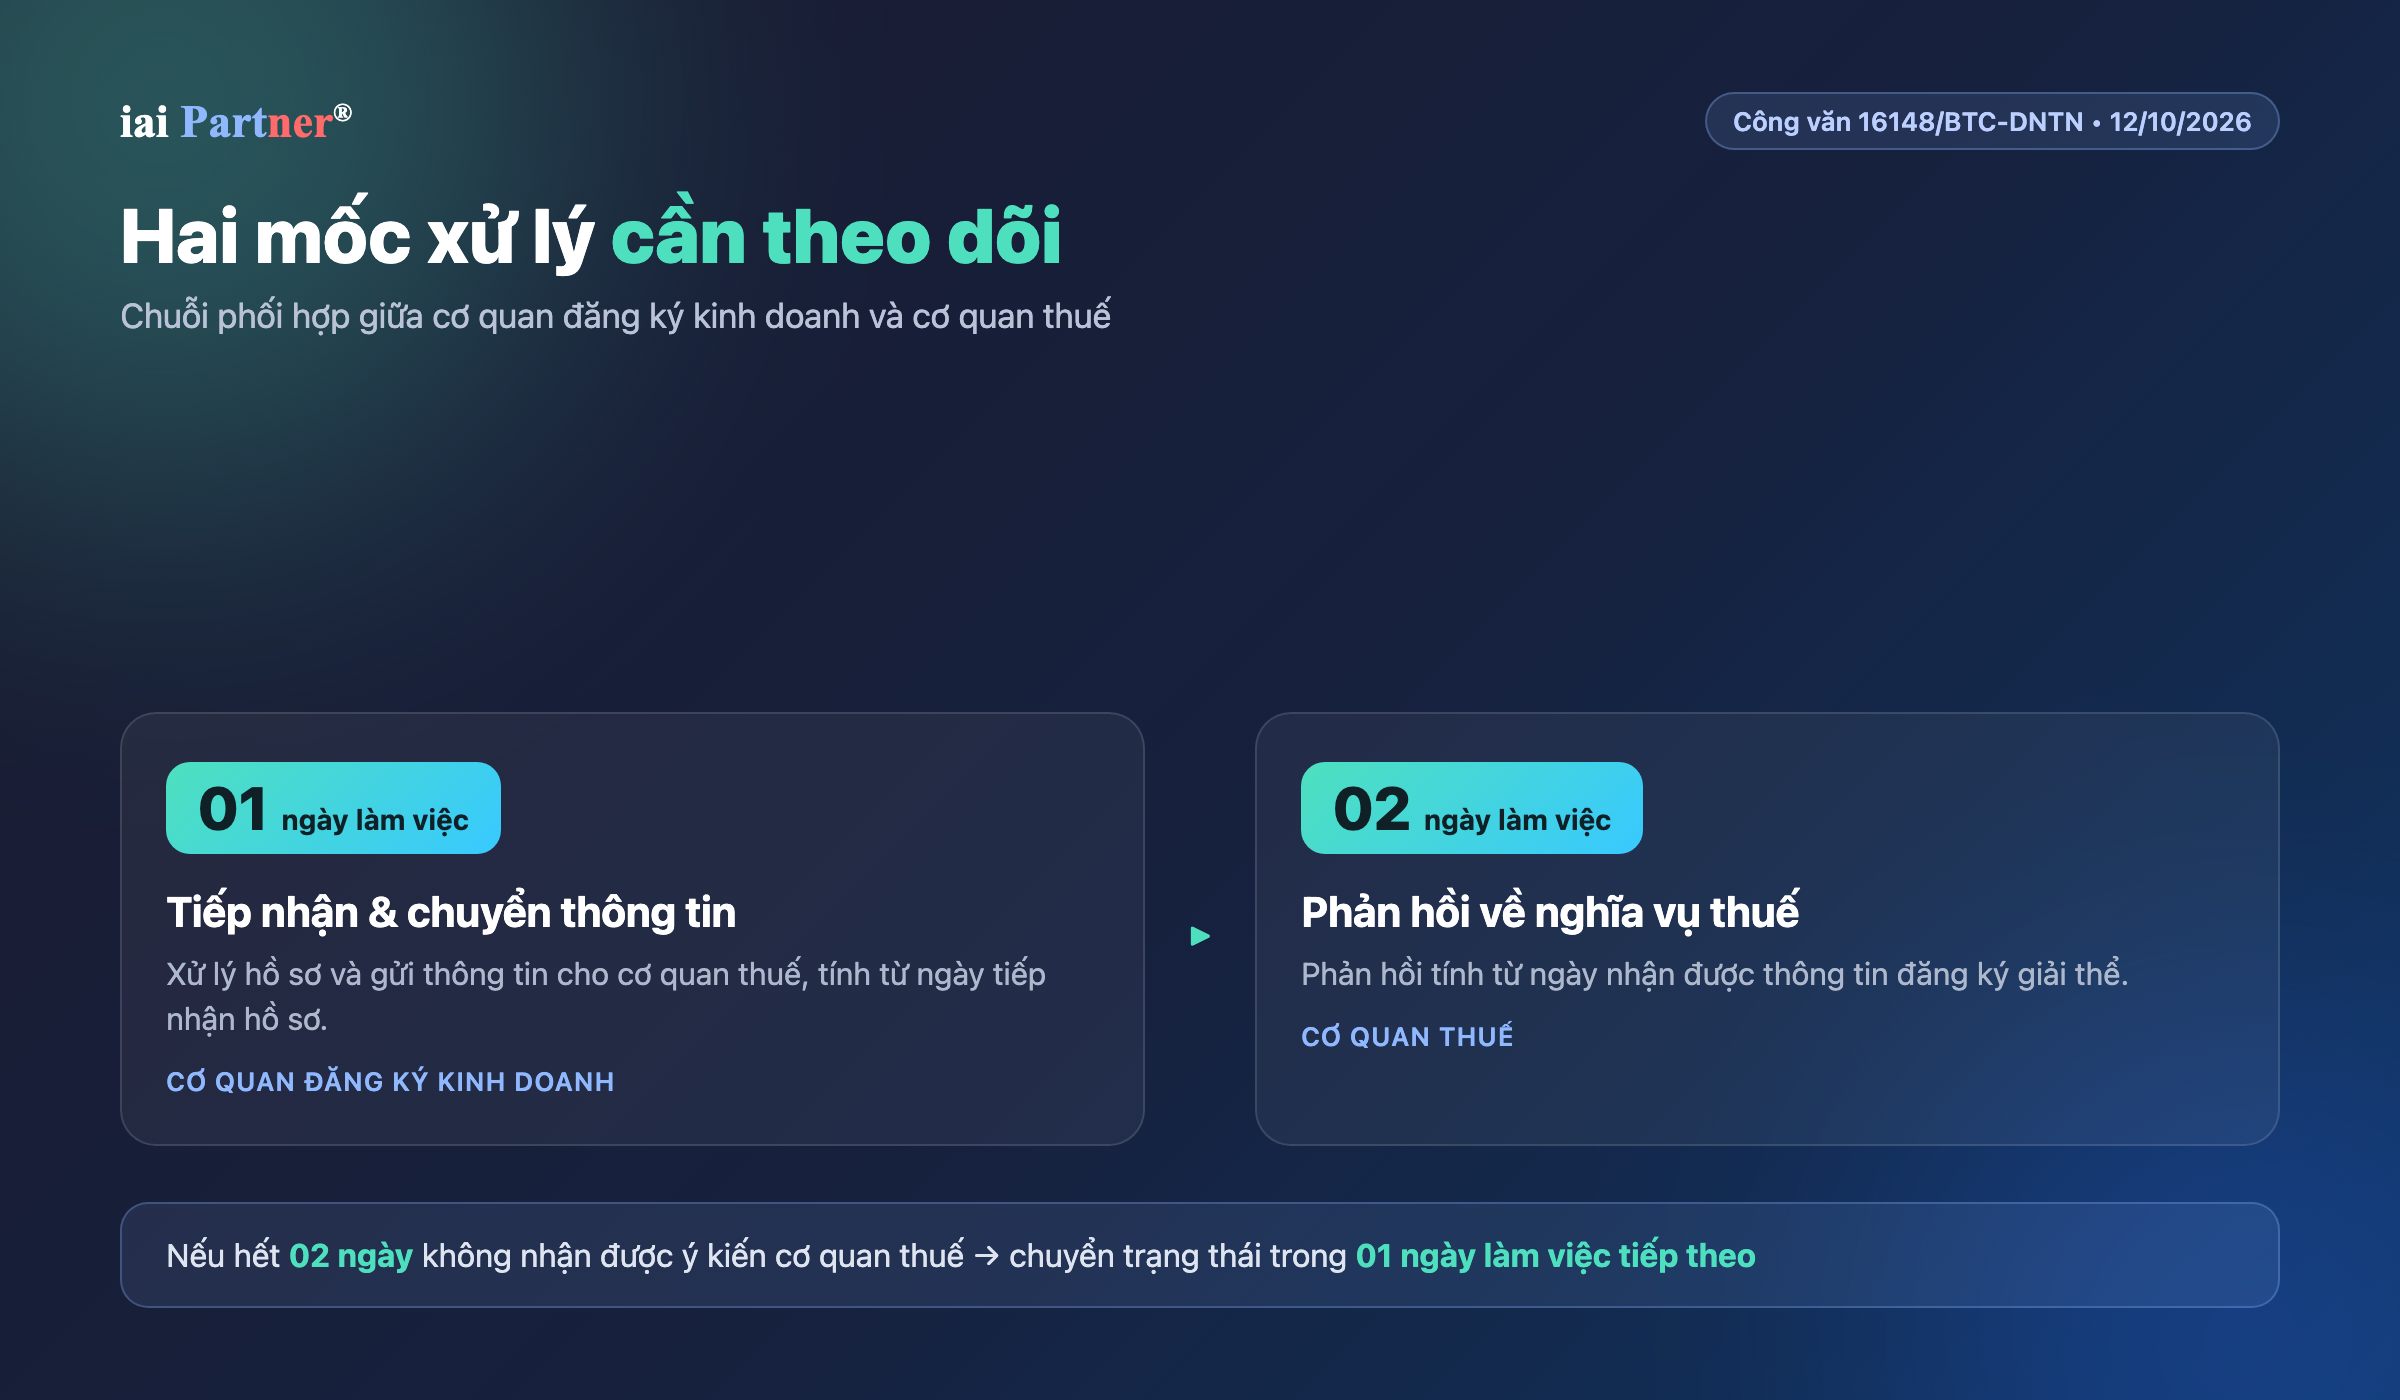
After the business files for dissolution, the business registration authority processes the file and sends information to the tax authority within 1 working day from receipt. The tax authority then has 2 working days from receiving the dissolution information to respond on tax obligations. These two milestones create a shorter and clearer coordination chain between the two authorities.
Processing chain between the two authorities
| Step | Deadline | Action |
|---|---|---|
| Business registration authority | 1 working day | Process the file and send information to the tax authority |
| Tax authority | 2 working days | Respond on tax obligations |
When is a business moved to “Dissolved” status?
The material identifies two situations. If the tax authority confirms that obligations have been completed, the business registration authority changes the status within 1 working day of receiving confirmation. If 2 working days pass after information is sent without feedback from the tax authority, the status change is carried out within the next 1 working day under the mechanism described in the source.
2 + 1 days
When no response is received from the tax authority
After 2 working days from sending the information, the status is changed within the next 1 working day.
ℹ️ System status should align with the actual file
Businesses should check both the system status and the outcome concerning tax obligations. A status change should not be interpreted more broadly than what the competent authority has actually confirmed.
The 180-day milestone is conditional, not “automatic dissolution”
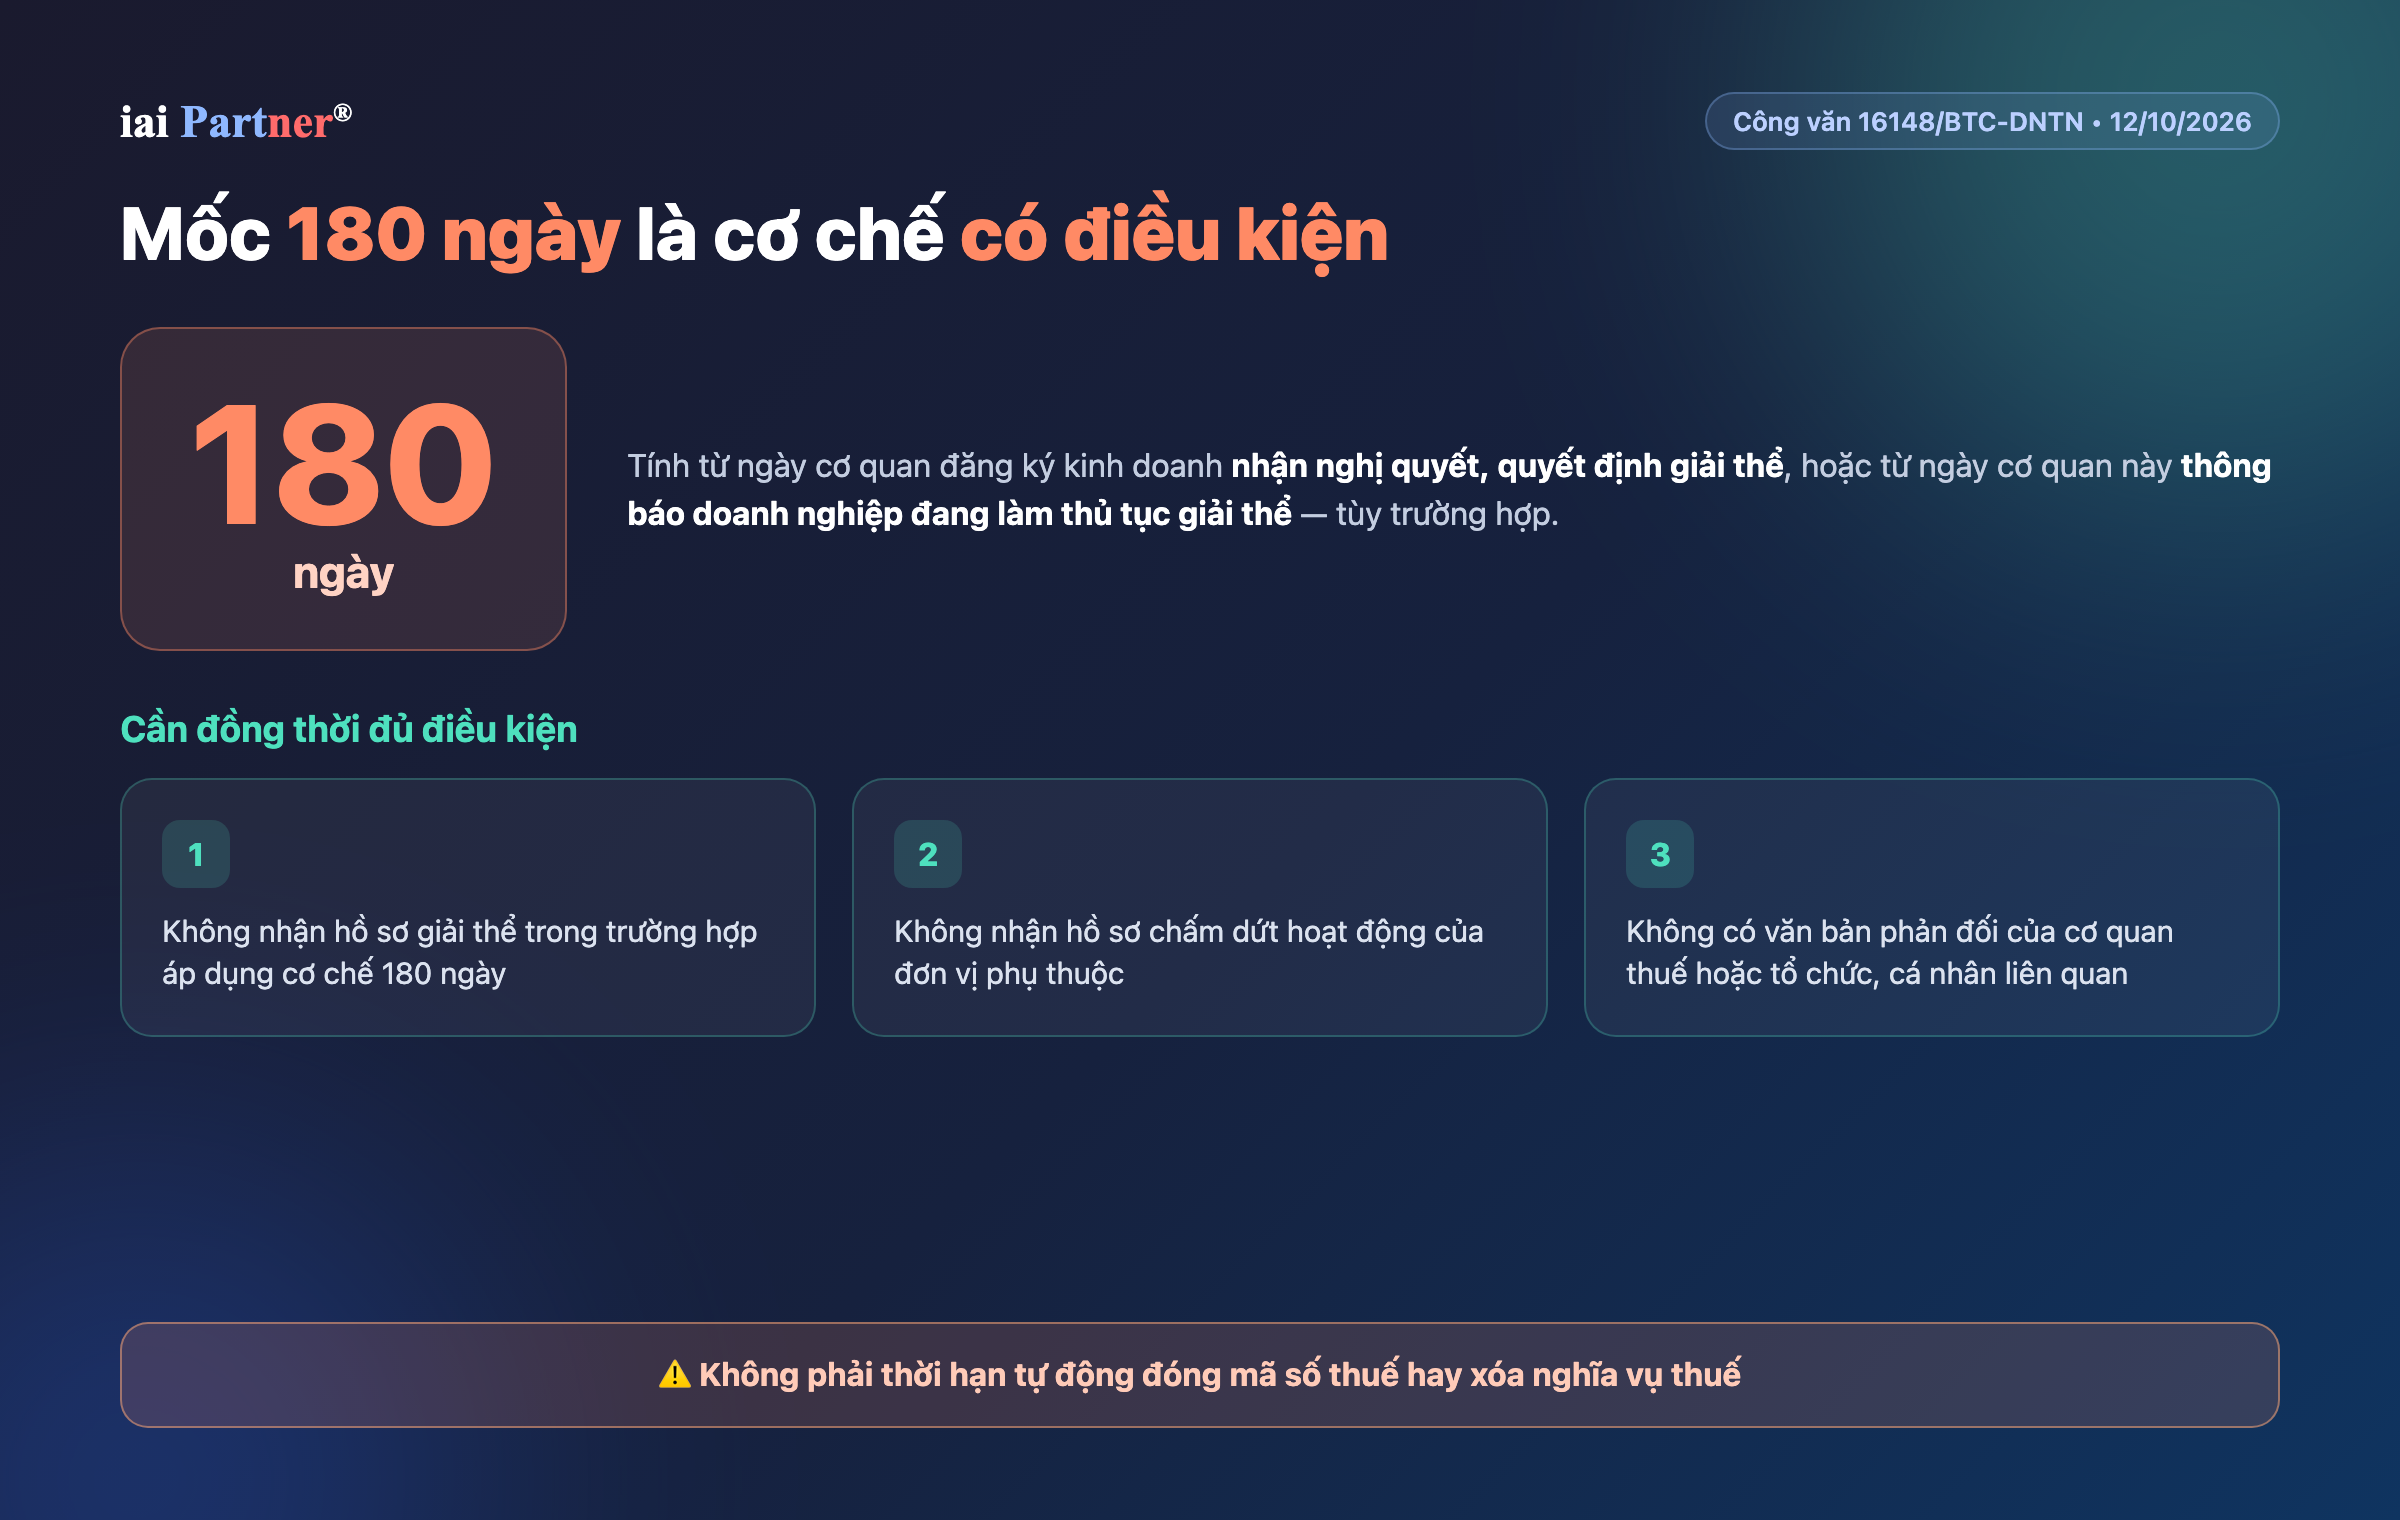
Mốc 180-day period is counted from the date the business registration authority receives the resolution or dissolution decision, or from the date it announces that the business is undergoing dissolution, depending on the case. But the passage of time alone is not sufficient. The source requires that no dissolution file or termination file for dependent units has been received and that there is no written objection from the tax authority or related organizations or individuals.
180-day
Conditional status-change milestone
It is not a deadline that automatically terminates the tax code or erases tax obligations.
| Condition | Requirement in the source |
|---|---|
| Dissolution file | No dissolution file is received in the case where the 180-day mechanism applies |
| Dependent units | No termination file for dependent units is received |
| Objections | No written objection from the tax authority or related organizations or individuals |
Processing outcome and what businesses should note
According to the source, once the conditions are met, the business is moved to “Dissolved”, while dependent units are moved to the status“Terminated” status. Under the mechanism described, the status change is carried out within 1 working day after the period expires . The key point is that legal status on the system does not mean all tax obligations are automatically erased.
⚠️ System errors do not remove the deadlines
The source states that when the system has errors, the two authorities must proactively coordinate to ensure response and processing deadlines. Businesses should keep this point in mind when a file has been accepted but the status has not been updated on schedule.
Enterprises should keep a timeline showing the filing date, the date information is sent to tax, the tax-response date and the status-update date. With this sequence, it is easier to identify which stage the file is in instead of searching through emails, messages and calls like an administrative treasure hunt nobody signed up for.
Related services at IAI Partner
Frequently asked questions
How long does the business registration authority have to send information to the tax authority?
According to the source, the deadline is 1 working day from receipt of the dissolution-registration file.
Does the 180-day milestone mean tax obligations automatically end?
No. The source emphasizes that the 180-day milestone is a conditional status-change mechanism and do not automatically erase tax obligations.
If the system has an error, can processing deadlines be ignored?
According to the source, no. The two authorities must proactively coordinate to ensure response and processing deadlines when the system has an error.
Recommendations from IAI Partner
Dear Valued Enterprise,
Official Letter 16148/BTC-DNTN makes the processing rhythm between the business registration authority and tax authority clearer. Enterprises should use these milestones to track progress proactively instead of simply waiting for the system status to change.
In particular, the 180-day milestone should be understood correctly as a conditional mechanism. Before relying on it, the business should check the complete file, any views from the tax authority and related organizations or individuals, and continue monitoring outstanding tax obligations.
IAI Partner recommends keeping the entire processing timeline, from filing date to response date and status-update date. This makes communication with authorities clearer and reduces the risk of mistaking a system status for completion of all obligations.
Sincerely,
iai Partner®
References
- Official Letter 16148/BTC-DNTN dated 12 October 2026 — The article's main source on accelerating the processing of business dissolution procedures.
- Government Newspaper – Request to minimize the time for carrying out business dissolution procedures — Official cross-reference source on the processing milestones and coordination mechanism.
- Decree 168/2025/NĐ-CP — The source document cites Clause 6 Article 64 and Clause 3 Article 65 for the conditional status-change mechanism.
- Decree 296/2026/NĐ-CP — The source document cites Article 13 on file-processing deadlines.
Source: IAI-Partner.com
Need help? Contact IAI Partner
📞 Hotline: 033 944 7112
📧 Email: hi@iai-partner.com
🌐 Website: iai-partner.com