

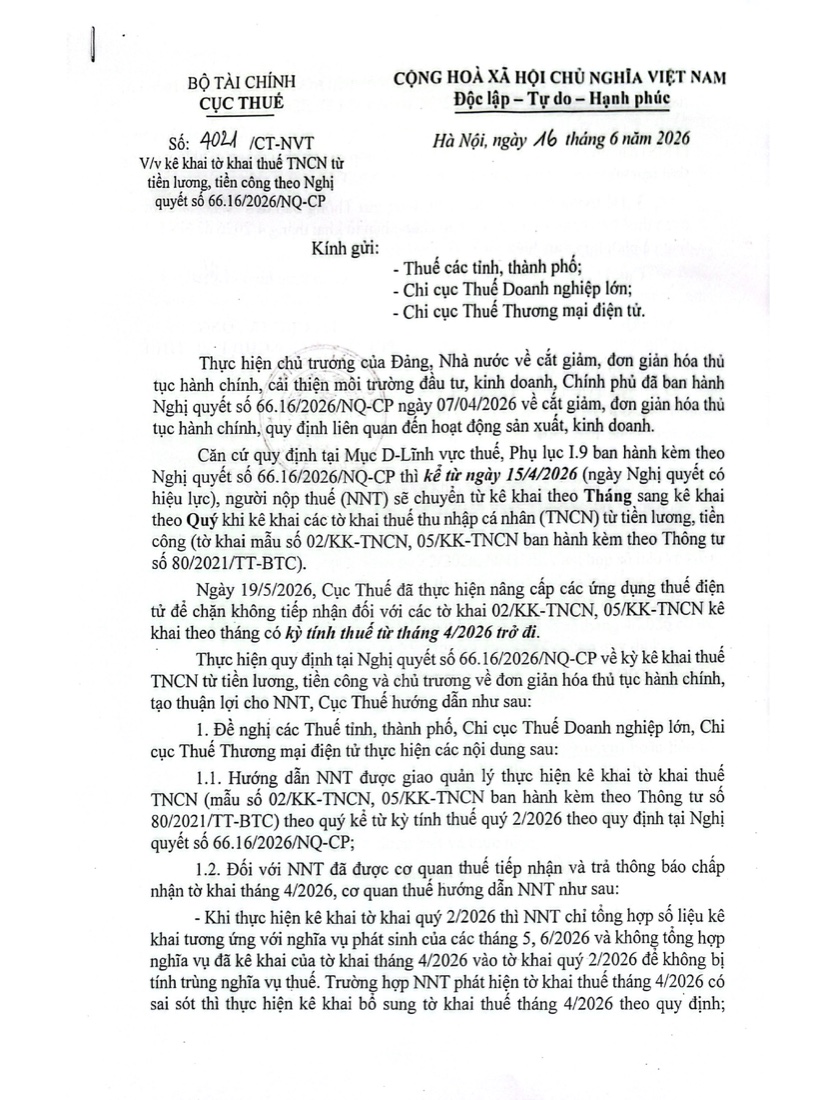
Quarterly personal income tax declaration is an important change for tax records from wages and salaries. Under Official Letter 4021/CT-NVT dated 16/6/2026 of the Tax Department, the change from monthly to quarterly declaration takes effect from the Quarter 2/2026 tax period.
The control issue is not only the change of declaration period. The enterprise must properly handle the accepted April 2026 declaration, avoid duplicating tax obligations when preparing the Q2 2026 declaration, and keep sufficient processing evidence.
Main change: from monthly declaration to quarterly declaration
According to the source content, PIT declarations for salary and wage income shift from a monthly declaration period to a quarterly declaration period. This change applies to declarations related to salary and wages under Circular 80/2021/TT-BTC. Enterprises should review their declaration calendar to avoid continuing submissions under the old habit.
The forms mentioned in the source document include 02/KK-TNCN and 05/KK-TNCN. From the Q2 2026 tax period, the file should be prepared quarterly. April 2026 must be handled carefully if the enterprise previously submitted the monthly declaration and it was accepted by the tax authority.
Internal milestone to remember: handle the submitted April 2026 declaration separately and do not duplicate tax obligations when preparing the Q2 2026 declaration.
Which declarations are affected according to the source document?
Not every tax file is mentioned in the source content. The focus of Official Letter 4021/CT-NVT is PIT declarations from salary and wage income. Therefore, enterprises should identify the correct file group before adjusting the declaration schedule.
| Details | Information to note |
|---|---|
| Tax type | PIT from salary and wage income |
| Declaration form | 02/KK-TNCN and 05/KK-TNCN |
| Form basis | Circular 80/2021/TT-BTC |
| New applicable period | Quarterly implementation starts from the Q2 2026 tax period |
| Guidance document | Official Letter 4021/CT-NVT dated 16 June 2026 of the Tax Department |
The table above helps accounting quickly identify which files need review. If the enterprise has many clients or member units, it should prepare a separate list for the group currently declaring PIT monthly. This helps avoid missing files when shifting to quarterly PIT declaration.
How to handle the accepted April 2026 declaration
The most important point of the Q2 2026 file is handling the April 2026 declaration that was previously submitted. If the April 2026 declaration has been received by the tax authority and has an acceptance notice, when preparing the Q2 2026 declaration, the enterprise should only aggregate obligations arising in May and June 2026.
The tax amount already declared for April 2026 should not be included again in the Q2 2026 obligation. If April is included in the quarterly declaration, the enterprise may duplicate tax obligations. This is a small error on a summary sheet, but its consequences are not small when review, adjustment, and explanation are required.
- If April 2026 has been accepted, do not add the April tax amount again to the Q2 2026 declaration.
- The Q2 2026 declaration only aggregates data arising in May and June 2026.
- If April 2026 contains errors, prepare a supplemental declaration for April 2026 in accordance with regulations.
- The PIT amount arising on the April 2026 declaration is paid according to the deadline of the Q2 2026 declaration.
- The deadline stated in the source document is 31 July 2026.
The focus is to avoid duplicating tax obligations when preparing the Q2 2026 declaration.
File review process for the responsible accountant
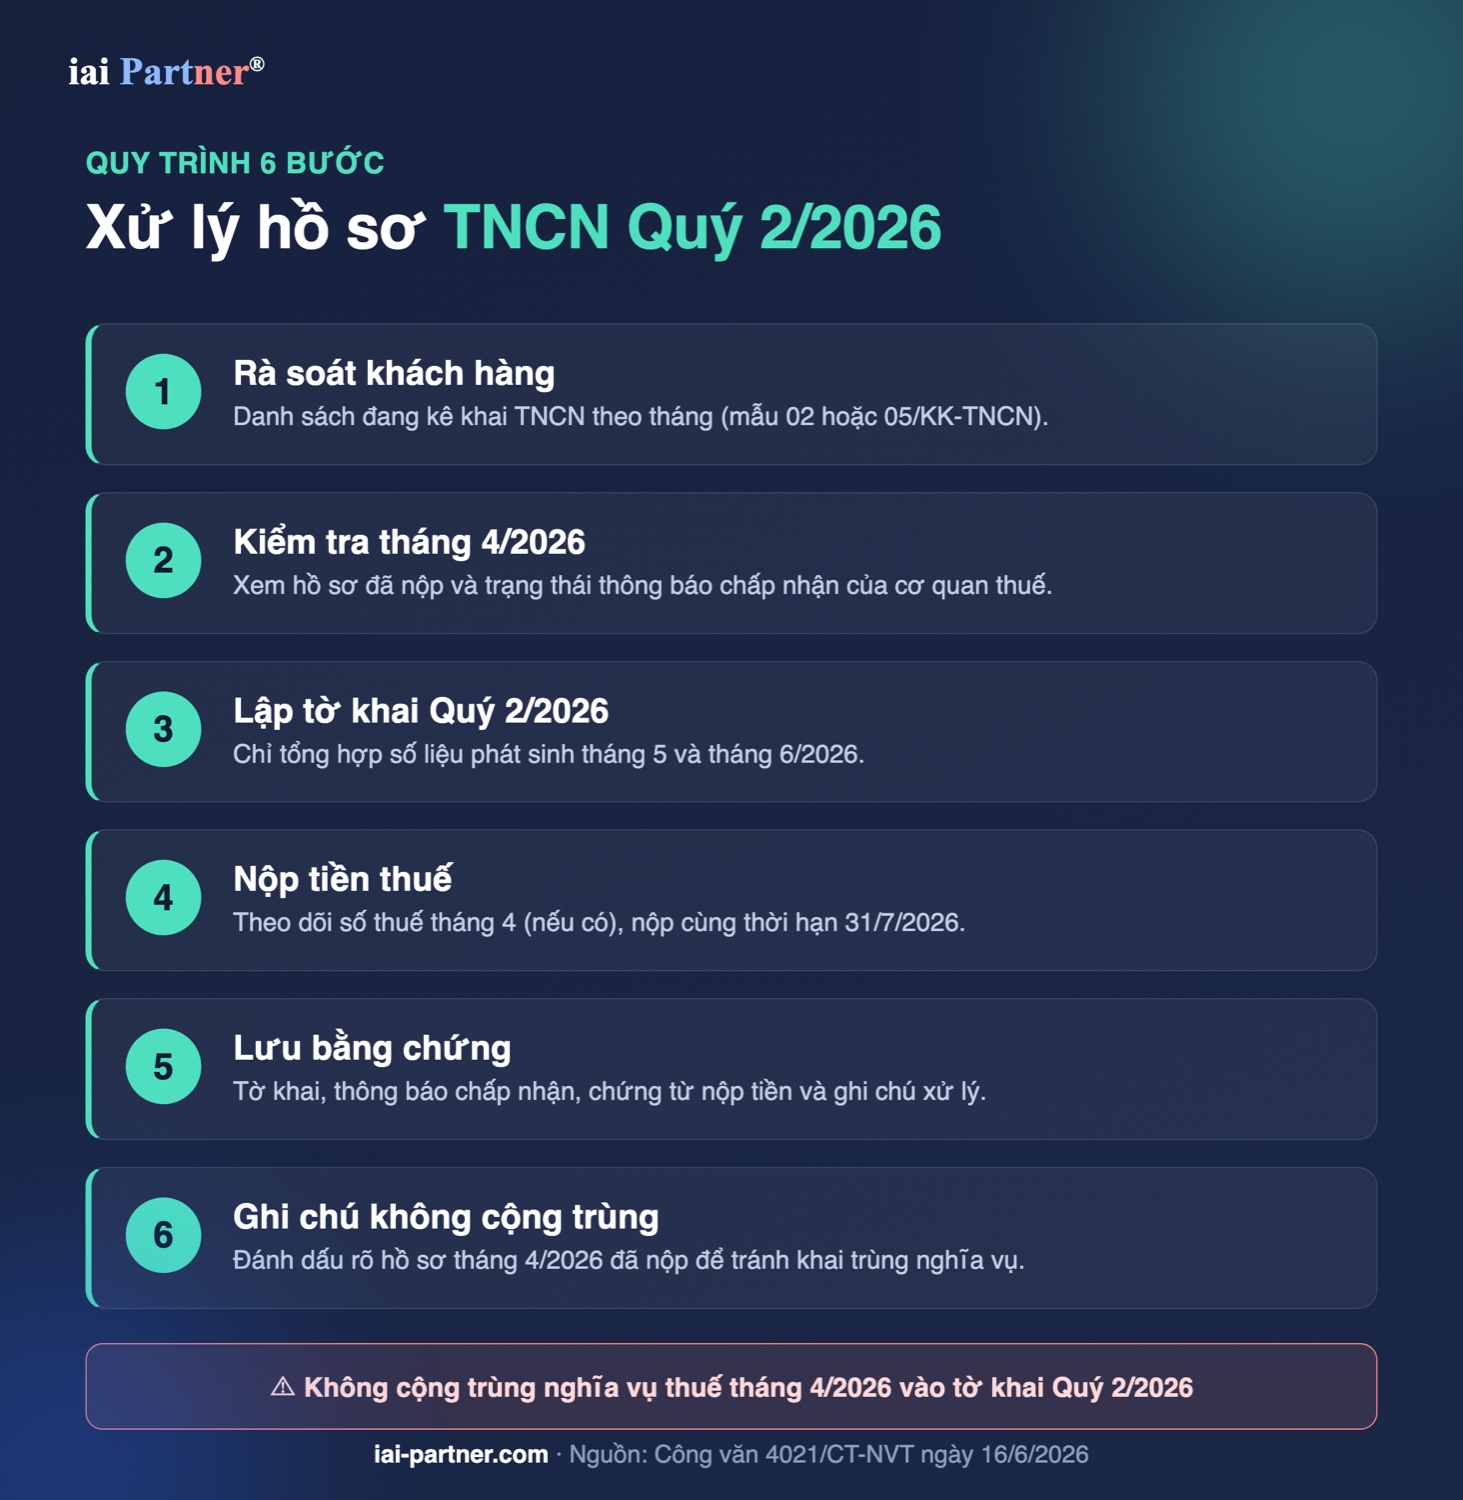
For consistent implementation, your enterprise should standardize the review process before preparing the Quarter 2/2026 file. This process suits in-house accounting, accounting service providers and tax-file control units. The goal is to correctly identify the client, the correct declaration period and the correct obligations to consolidate.
- Step 1: Review the list of clients currently declaring PIT monthly.
- Step 2: Identify clients with form 02/KK-TNCN or 05/KK-TNCN.
- Step 3: Check the April 2026 file and the status of the tax authority's acceptance notice.
- Step 4: Prepare the Q2 2026 declaration with May and June 2026 data if April has already been declared.
- Step 5: Track the April 2026 tax amount, if any, and pay it by the Q2 2026 deadline.
- Step 6: Keep the declaration, acceptance notice, payment documents, and processing notes.
The Q2 2026 file should have a clear note in the management file. The note should state that April 2026 is not duplicated if the client has submitted the April declaration. This note helps reviewers immediately understand the handling approach instead of tracing each notice like data archaeology.
Q2 2026 file handover checklist
Before sending a completion report to the client or management, accounting should recheck the entire file. A checklist reduces the risk of missing documents, forgetting notice status, or duplicating tax amounts. For files involving a period transition, final control is always more valuable than one supplemental correction.
| Check item | Required status |
|---|---|
| Identify related files | Clients with salary and wage PIT declarations have been identified |
| Check April 2026 | The April 2026 declaration and acceptance notice have been checked |
| Prepare the Q2 2026 declaration | Include only May and June if April has been submitted |
| Pay the April 2026 tax amount | The tax amount payable and the 31 July 2026 deadline have been checked |
| Handle errors | A supplemental April 2026 declaration has been prepared if errors were found |
| Keep the file | Documents and processing notes have been kept for internal review |
From Q2 2026, enterprises need to manage PIT files quarterly. April 2026 should be marked as a special period for separate review. If a client has submitted April, the handover file should clearly show the handling method to avoid misunderstandings in later checks.
Notification content that may be sent to clients
After reviewing the April 2026 file, the enterprise or service provider may send a short notice to clients. The content should clearly explain the change in declaration period, how the accepted April declaration is handled, and the review commitment to avoid duplicate declaration. The notice should use clear language and avoid overly long quotations.
According to Official Letter 4021/CT-NVT dated 16 June 2026, PIT declarations from salary and wage income will shift from monthly declaration to quarterly declaration from Q2 2026.
If the April 2026 declaration has been accepted by the tax authority, when preparing the Q2 2026 declaration, only data arising in May and June 2026 should be aggregated; the obligation already declared for April 2026 must not be duplicated.
A suitable closing sentence could be: IAI will review and update the Q2 2026 file to avoid duplicate tax obligation declaration. This content is concise, focused, and helps clients understand why the quarterly file does not add April again.
Common risks when shifting to quarterly declaration
When the declaration period changes, the risk often lies not in major rules but in small operations. Enterprises may forget to check the April acceptance notice, add April data again in Q2, or fail to keep payment documents. These errors make the file difficult to control when later review is needed.
| Risk | Control method |
|---|---|
| Duplicating the April 2026 obligation | Clearly note that the April file has been submitted and only May and June are aggregated |
| Not checking the acceptance notice | Keep the acceptance notice before preparing the Q2 2026 declaration |
| Forgetting to pay the April 2026 tax amount | Track the April tax amount and the 31 July 2026 deadline separately |
| April errors adjusted in the quarterly declaration | Prepare a supplemental April 2026 declaration in accordance with regulations |
| Missing handover evidence | Keep declarations, payment documents, and processing notes in the client file |
The important control point is not to handle files by intuition. Each file needs a clear trail: whether it has been submitted, whether it has been accepted, how April was handled, and which months Q2 aggregates. Quarterly PIT declaration will be smoother if data is standardized from the first applicable period.
Frequently asked questions
From which period does quarterly PIT declaration start?
According to the source content, PIT declarations from salary and wage income start being implemented quarterly from the Q2 2026 tax period.
If the April 2026 declaration has been accepted, how should Q2 2026 be declared?
If April 2026 has been accepted and has an acceptance notice, the Q2 2026 declaration only aggregates May and June 2026 data.
How should errors in the April 2026 declaration be handled?
The enterprise should submit a supplemental declaration for April 2026 in accordance with regulations, not adjust it by adding it back to the Q2 2026 declaration.
Recommendations from IAI Partner
Dear Valued Enterprise,
Quarterly PIT declaration from Q2 2026 should be implemented together with a separate review of submitted April 2026 files.
The enterprise should prepare a list of files accepted by the tax authority, note how April was handled, and keep complete payment evidence.
Need support? IAI Partner can accompany the enterprise in reviewing PIT files, checking declaration periods, and standardizing handover files.
Sincerely,
iai Partner®
Source: Official Letter 4021/CT-NVT dated 16/6/2026 of the Tax Department · IAI-Partner.com
Need help? Contact IAI Partner
📞 Hotline: 033 944 7112
📧 Email: hi@iai-partner.com
🌐 Website: iai-partner.com