

The Q2/2026 tax return is an issue business households and individual businesses need to review carefully when applying the revenue threshold of 01 billion VND or less.
According to the internal source, the conclusion that no quarterly return is required is correct only when the business is within the threshold and has not exceeded it.
Main conclusion for Q2/2026
Regarding value-added tax and personal income tax from ordinary business activities, household and individual businesses with 2026 revenue of 01 billion VND or less are not required to file the Q2/2026 tax return. However, this conclusion does not mean the household business need not monitor its revenue. Revenue remains an important basis for determining when the obligation to declare and pay tax arises. Therefore, when advising or self-reviewing files, your enterprise should clearly separate two things: not filing the quarterly return, and still having to report revenue by the prescribed deadline.
The most common confusion is between exemption from quarterly filing and exemption from all tax administration obligations. If expected annual revenue and actual revenue have not exceeded 01 billion VND, no Q2/2026 VAT and PIT return is filed. If cumulative revenue exceeds 01 billion VND in Q2, declaration and payment obligations arise from Q2/2026 itself. This point should be settled early, because faith-based revenue management does not replace a tax return.
Not filing the Q2/2026 tax return does not mean there is no need to monitor, record, or notify revenue.
Authorities in the source and how to understand the 01 billion VND threshold
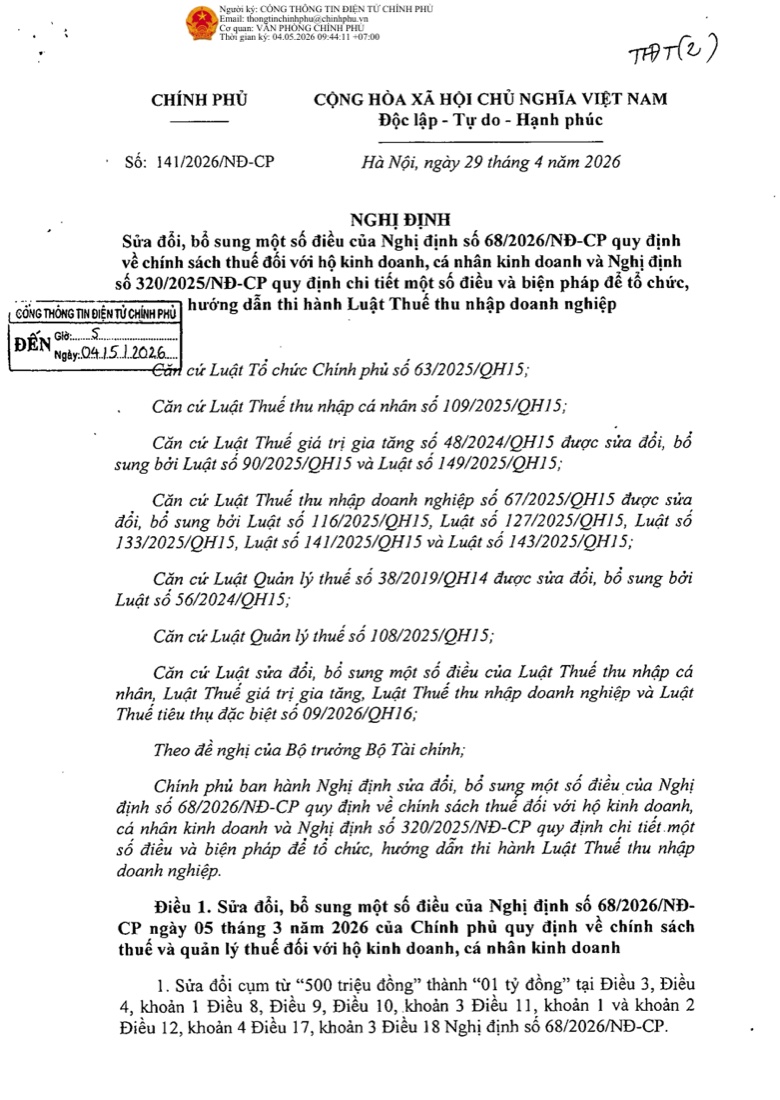
The source states that Decree 68/2026/NĐ-CP and Decree 141/2026/NĐ-CP are the main bases for determining 2026 tax obligations. Decree 141/2026/NĐ-CP changes the phrase 500 million VND to 01 billion VND in many provisions of Decree 68/2026/NĐ-CP. Therefore, records and guidance should use 01 billion VND or less instead of under 01 billion VND. Revenue exactly equal to 01 billion VND is also within the threshold.
The source also mentions Clause 1, Article 8 of Decree 68/2026/NĐ-CP on self-determining revenue and filing from the quarter in which the threshold is exceeded. Article 9 applies to new businesses in the year, with revenue notification milestones on 30/6 or 31/12. Article 10 and Clause 3, Article 8 are used to determine the quarterly filing deadline as the last day of the first month of the following quarter. For Q2/2026, the source identifies 31/07/2026 as the filing deadline if filing is required.
| Legal basis | Content stated in the source | Processing meaning |
|---|---|---|
| Decree 141/2026/NĐ-CP | Changes 500 million VND to 01 billion VND in many provisions of Decree 68/2026/NĐ-CP | Updates the revenue threshold applied in 2026 |
| Decree 68/2026/NĐ-CP | Annual revenue of 01 billion VND or less is not subject to VAT and is not required to pay PIT | Basis for determining no quarterly return is required when the threshold is not exceeded |
| Article 9 of Decree 68/2026/NĐ-CP | New businesses in the year notify revenue by the 30/6 or 31/12 milestones | Determines the revenue notification deadline for new business cases |
Case of stable ongoing business
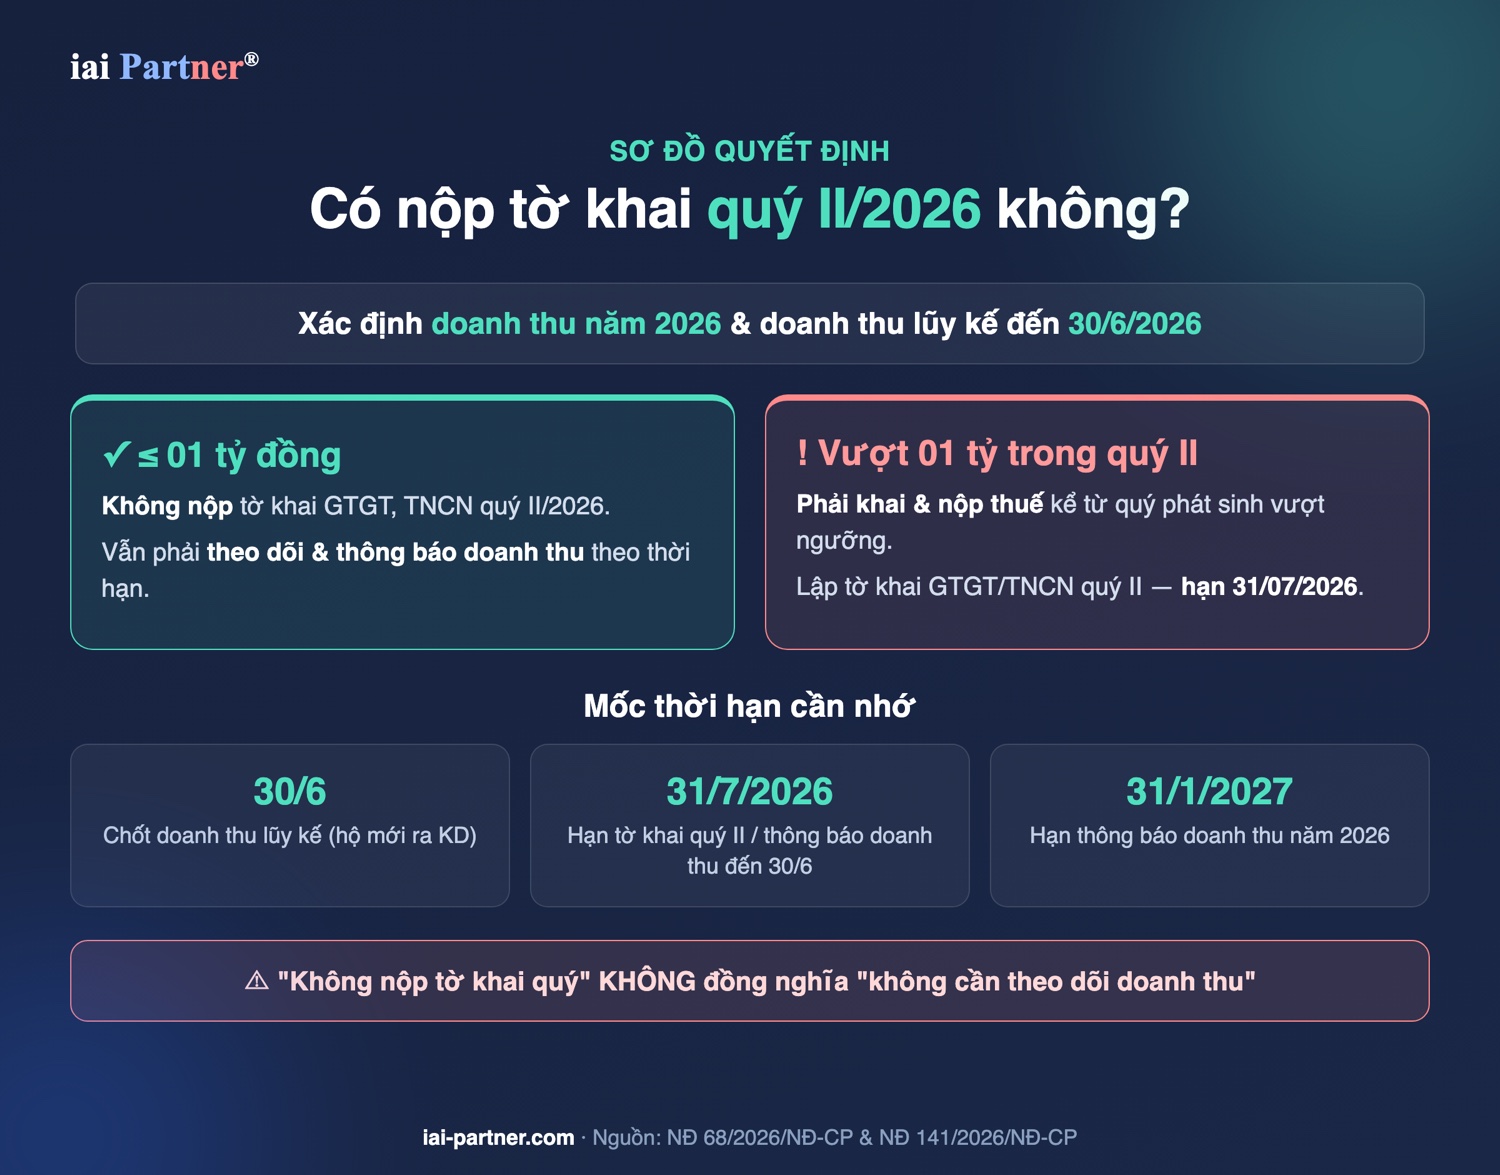
For stable ongoing businesses, the control focus is 2026 revenue and actual cumulative revenue through the end of Q2. If expected full-year revenue is 01 billion VND or less and the threshold has not been exceeded in Q2, no Q2/2026 tax return is filed. After 2026, revenue notification is made by the deadline stated in the source. Accounting should maintain a monthly cumulative revenue table with alerts near the threshold.
If cumulative revenue exceeds 01 billion VND in Q2/2026, declaration and tax payment are required from the quarter in which the threshold is exceeded. The Q2 file should then be prepared, including the Q2 VAT and PIT return and the tax amount payable under applicable rules. The source states the Q2 filing deadline as 31/07/2026. This deadline should not be handled at the last minute because revenue and sales documents often need reconciliation.
- Determine expected 2026 revenue before concluding that no quarterly return is required.
- Track actual cumulative revenue through 30/6/2026.
- Declare and pay tax from Q2 if cumulative revenue exceeds 01 billion VND in Q2.
Case of newly starting business in the first six months of 2026
For businesses newly starting in the first six months of 2026, 30/6/2026 is the first control milestone. If actual revenue through that date is 01 billion VND or less, no Q2/2026 tax return is filed. However, revenue through 30/6 must still be notified no later than 31/07/2026. If the threshold continues not to be exceeded in the last six months, revenue for that period is notified no later than 31/01/2027.
If cumulative revenue exceeds 01 billion VND in any quarter, declaration and tax payment obligations are triggered from that quarter. Revenue tracking records should not be prepared merely for show while expecting the tax system to guess the rest. Businesses should check the start date, actual revenue, expected annual revenue, and special activities. These factors determine whether not filing the quarterly return is safe or merely premature.
| Situation | Revenue condition | Required file | Deadline or result |
|---|---|---|---|
| Operating steadily | 2026 revenue is 01 billion VND or less and Q2 has not exceeded the threshold | Do not file the Q2 VAT and PIT return; continue monitoring revenue | Notify 2026 revenue no later than 31/01/2027 |
| Newly starting business in the first six months | Actual revenue through 30/6/2026 is 01 billion VND or less | Do not file the Q2 return; notify revenue through 30/6 | No later than 31/07/2026 |
| Exceeds 01 billion VND in Q2 | Cumulative revenue exceeds 01 billion VND in Q2/2026 | File the Q2 VAT and PIT return; calculate and pay tax | The Q2 filing deadline is 31/07/2026 |
Points not to misunderstand when advising or self-reviewing
The 01 billion VND threshold in the source is used for VAT and PIT from ordinary business activities. The source also notes that other obligations should be checked, including excise tax, natural resources tax, environmental protection tax, real estate leasing, declaration or payment on behalf, and e-invoices. Therefore, one statement that no quarterly return is filed should not be used to conclude all tax obligations. A business household may not file the Q2 VAT and PIT return but may still have other obligations to check separately.
- Do not write under 01 billion VND if the content includes exactly 01 billion VND.
- Do not say nothing needs to be done, because revenue still needs tracking and notification.
- Do not make a general conclusion when special activities or filing/payment on behalf obligations exist.
Need support? IAI Partner can help your enterprise review household-business files, determine whether a Q2/2026 tax return must be filed, build a revenue-tracking sheet and standardize the wording used to guide clients. The right approach is to determine the business status, actual revenue, projected revenue and any special obligations before drawing a conclusion. Doing it right from the start helps reduce the risk of missing a return, missing a revenue report, or using the wrong threshold when explaining to clients.
Frequently asked questions
Must a business household with revenue of 01 billion VND or less file the Q2/2026 tax return?
According to the source, if 2026 revenue is 01 billion VND or less and the threshold has not been exceeded in Q2, no Q2/2026 VAT and PIT return is required.
Does not filing the Q2 return mean revenue notification is not required?
No. Business households and individual businesses must still monitor, record, and notify revenue by the corresponding deadlines stated in the source.
How should it be handled if revenue exceeds 01 billion VND in Q2/2026?
The business household or individual business must declare and pay tax from the quarter in which the threshold is exceeded. For Q2/2026, the source states the deadline as 31/07/2026.
Recommendations from IAI Partner
Dear Valued Enterprise,
IAI Partner recommends not concluding filing obligations based only on estimated revenue.
Check the business start date, actual cumulative revenue, expected annual revenue, and any special activities.
For business household client files, keep a revenue tracking table and notification milestones to avoid missing deadlines.
Sincerely,
iai Partner®
Source: Decree 68/2026/NĐ-CP dated 05/03/2026 · Decree 141/2026/NĐ-CP dated 29/04/2026 · IAI-Partner.com
Need help? Contact IAI Partner
📞 Hotline: 033 944 7112
📧 Email: hi@iai-partner.com
🌐 Website: iai-partner.com