

Supplementary tax filing is common when a business discovers errors or omissions in a submitted return. Under Tax Administration Law No. 108/2025/QH15, the supplementary filing period is determined as no more than 05 years. Businesses should review old records early to avoid missing the handling window.
The key point is that the 05-year period is counted from the filing deadline of the period with the error or omission. It is not counted from the date the business discovers the issue internally. Correct understanding helps chief accountants prioritize tax periods nearing expiry first.
What changes under the new rule?
Clause 5, Article 12 the Law on Tax Administration No. 108/2025/QH15 is the main legal basis for the supplementary declaration time limit. Taxpayers who discover errors or omissions in a filed tax return or other payment may make a supplementary declaration. However, the time to do so is limited to 5 years from the deadline for filing the original return.
| Details | Point to remember | Impact on businesses |
|---|---|---|
| Supplementary filing period | No more than 05 years from the original filing deadline | Review old tax periods by priority |
| Main effective date | Applies from 01/07/2026 according to the verified source | Businesses should update processes before application |
| Compared with the old rule | The old period was 10 years, and the new period is 05 years | The window for handling errors is significantly shortened |
Core principle: 05 years are counted from the original filing deadline, not from the date the error is discovered.
How to calculate the 05-year period
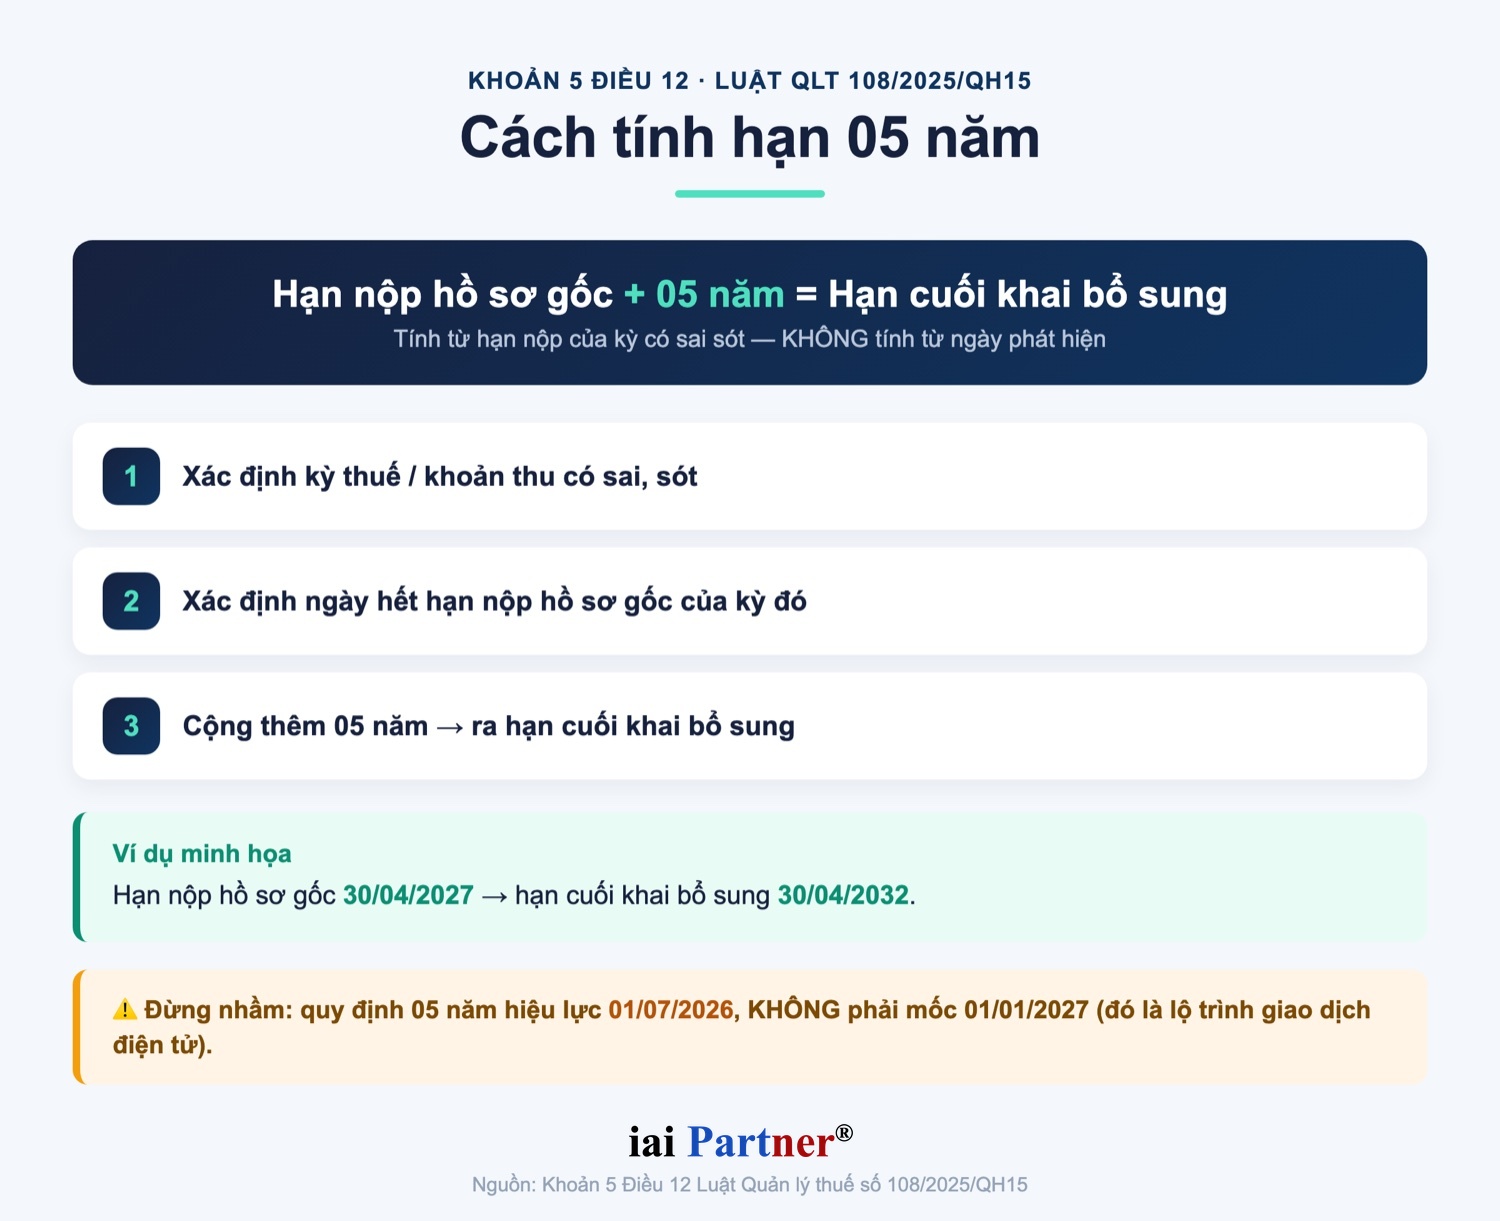
The calculation should start from the original return of the period with the error. The business identifies the last day for submitting that period's return, then adds 05 years. If the error is discovered after that point, the responsible team should not file on its own and should assess the handling approach.
| Step | Action required |
|---|---|
| Step 1 | Identify the tax period or other revenue item with the error or omission |
| Step 2 | Identify the original filing deadline for that period |
| Step 3 | Add 05 years to determine the final supplementary filing deadline |
For example, if the original filing deadline is 30/04/2027, the final supplementary filing deadline under this principle is 30/04/2032. The example only illustrates how to add the period and does not replace reviewing the specific file status. Businesses still need to check whether the file has been inspected, audited, or subject to an explanation request.
Points that must not be confused
The 05-year rule should not be confused with the 01/01/2027 milestone. The 01/01/2027 milestone relates to the roadmap for completing electronic transactions in tax administration. It is not the start date for applying the 05-year rule on supplementary tax filing.
Risks of incorrect interpretation
- Counting 05 years from the error discovery date instead of the original filing deadline
- Assuming the 05-year rule starts applying only on 01/01/2027
- Equating the supplementary filing period with sanction or tax collection limitation periods
- Filing supplements on one's own when the file is already under inspection or audit
- Not retaining explanation files and documents supporting adjusted figures
Do not say that the 05-year rule only applies from 01/01/2027.
Process for reviewing old files
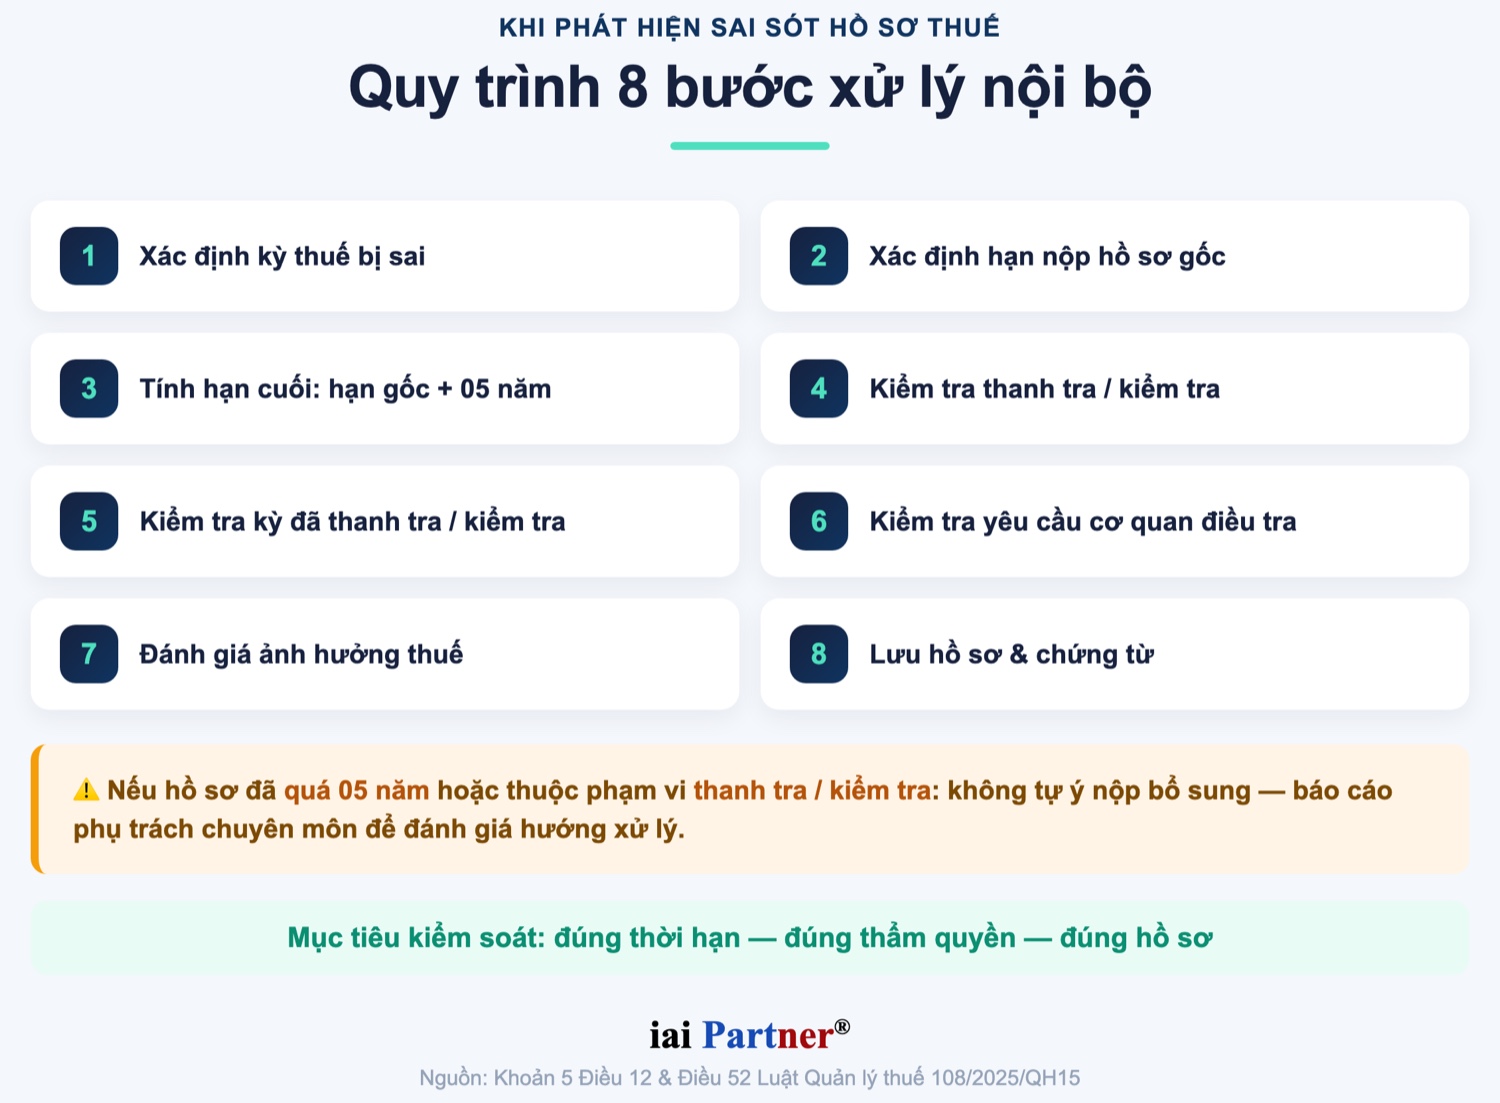
Businesses should list tax periods that may still be eligible for supplementary filing before handling each file. Periods approaching the 05-year mark should be reviewed first. This helps chief accountants control deadlines, inspection risks, and tax impacts arising from adjustments.
Handling checklist when an error is discovered
- Identify the tax period and type of file with the error or omission
- Identify the original filing deadline for the period with the error
- Calculate the final supplementary filing deadline as the original deadline plus 05 years
- Check whether the file has been inspected, audited, or subject to an explanation request
- Assess affected increases, decreases, exemptions, refunds, or deductible tax amounts
- Retain explanation files, supporting documents, and internal approval decisions
If a filing is past the 5-year limit or involves an audit or inspection, the business should not handle it by old habit. In this case, it needs corporate tax records advisory to reassess the legal basis, the status of the filing and detailed guiding documents. A cautious approach reduces the risk of self-filing errors or submitting inappropriate records.
What should businesses do now?
Your business should update on new tax policies and the supplementary declaration process before the new rules are stably applied. The focus is the list of tax periods, original filing deadlines, audit status and supporting documents. When a filing is near its limit, the business should place it on the priority list.
The accounting team should also align wording when communicating with management and clients. A suitable statement is that the 05-year rule belongs to Clause 5, Article 12 of Tax Administration Law No. 108/2025/QH15, with the main effective date from 01/07/2026. This content should not be interpreted as the 01/01/2027 milestone.
A consistent way to phrase it when advising
How does IAI Partner support businesses?
Corporate accounting service by IAI Partner can help your business review the list of old tax filings, identify periods nearing their limit and standardize explanatory documents. For cases with audit, inspection or overdue risk, the filing needs closer assessment. Need support? IAI Partner can accompany you to reduce errors during preparation.
Recommendations from IAI Partner
Dear Valued Enterprise,
IAI Partner recommends that businesses review tax periods still within the 05-year scope. This list should show the original filing deadline, final supplementary filing deadline, and inspection or audit status. When data is standardized, the accounting team can more easily prioritize files requiring earlier handling.
Businesses should also align communication about the effective date. The 05-year rule should be linked to Clause 5, Article 12 of Tax Administration Law No. 108/2025/QH15 and the main effective date of 01/07/2026. Confusing it with 01/01/2027 may delay the review plan.
Need support? IAI Partner can assist with building file checklists, checking deadlines, and standardizing explanation documents. A systematic approach helps businesses control risk more effectively. This should be implemented early, especially for businesses with many tax periods to review.
Sincerely,
iai Partner®
Source: IAI-Partner.com
Frequently asked questions
From which date is the 05-year supplementary filing period counted?
Under this rule, the period is counted from the filing deadline of the tax period with the error or omission. It is not counted from the date the business discovers the issue.
Is 01/01/2027 the application date of the 05-year rule?
No. The verified source shows that the main provisions of Tax Administration Law No. 108/2025/QH15 take effect from 01/07/2026, while the 01/01/2027 milestone relates to the electronic transaction roadmap.
Can a file already inspected or audited be supplemented independently?
Businesses should not handle it independently if the file is under inspection, audit, or a request from a competent authority. They need to assess the file status and detailed guidance before acting.
Need help? Contact IAI Partner
📞 Hotline: 033 944 7112
📧 Email: hi@iai-partner.com
🌐 Website: iai-partner.com